
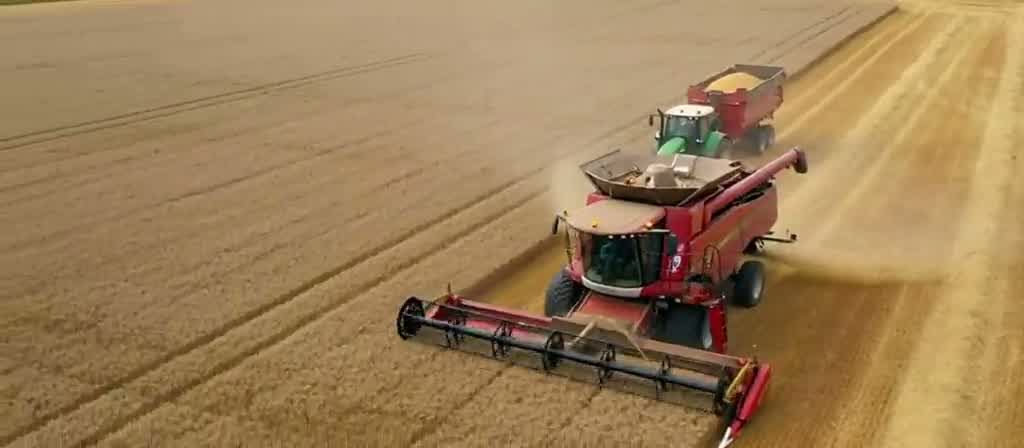
How do you finance a £200,000 combine before harvest?
Compare seasonal repayments and part exchange on a £200,000 combine. Work out the net trade in value, the cash due at delivery and the timing of the first payment.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersA panel of lenders, not one bank
- 5.0 from 20 Google reviews
- No credit checkEnquiring leaves no mark on your file
Get the dealer’s trade in value and the lender’s settlement figure before comparing quotes. Deduct the settlement from the trade in value to find the equity available for the replacement. Ask for both monthly and seasonal repayment schedules and test both against when crop receipts actually reach the bank.
What is the part exchange worth after settlement?
Suppose a replacement combine costs £200,000 excluding VAT. The dealer offers £65,000 for the outgoing machine and its existing lender quotes a £25,000 settlement. The net credit is £40,000. If the new lender accepts that credit in full and there are no other adjustments, £160,000 of the purchase price remains to fund before VAT, fees or any further deposit. These figures are illustrative.
Ask the dealer to separate the purchase price from the trade in allowance, and check who pays the settlement and when it expires. Confirm the VAT shown on both invoices and have your accountant check the treatment. If the settlement exceeds the trade in value, account for the shortfall separately.
Are seasonal payments better than monthly payments?
| Check | Monthly schedule | Seasonal schedule |
|---|---|---|
| When cash goes out | Regular payments throughout the year. | Payments on dates agreed with the lender, potentially larger in months with more receipts. |
| What to stress test | Whether the farm can cover payments before crops sell. | Whether a large payment still fits if a buyer pays late or the farm holds grain in store. |
| How to compare cost | Compare written schedules using the same asset price, net trade in credit and term. Include fees and any final payment. | |
Use the expected dates of customer receipts, including grain contracts, rather than the harvest date alone. Ask when the first payment is due and whether a different schedule changes the total payable.
What should the farm send before ordering?
- The dealer quote showing the combine, header and any options separately.
- The trade in offer and a dated settlement statement for the outgoing machine.
- Recent accounts and a cash flow forecast that shows crop receipts and other commitments.
- Expected delivery, acceptance and collection dates, including any overlap between the two machines.
CW Asset Finance is a credit broker. Share the dealer quote, trade in terms and preferred payment months to compare options. All finance is subject to status, affordability and lender approval.
See combine harvester finance and combine harvester prices.
Common questions
Answers to help you plan your purchase.
Can part exchange equity count towards the deposit?
Ask the new lender whether it will accept the net credit after settlement and how the dealer should show it on the paperwork.
Can I move a seasonal payment after signing?
The contract specifies the due dates. If cash flow changes, speak to the lender before a payment falls due and obtain written agreement to any change.
Can I put the header on the same agreement?
List the header separately on the quote and ask whether the lender can include it with the combine.

Written and reviewed by Conor Hull, founder of CW Asset Finance.
Last reviewed 19 November 2026. About Conor
An independent asset finance broker in Tadcaster, North Yorkshire, working with more than 60 lenders. When you ring, Conor answers, and he speaks to the underwriter on your proposal himself.
CW Asset Finance is a trading name of Conor William Hull, an Appointed Representative (FRN 1031964) of Rural Finance Limited, authorised and regulated by the Financial Conduct Authority (FRN 630701). We are a credit broker, not a lender.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Total repayable about £,
Illustrative only, not a quote. Flat rates are indicative, subject to status and are not an APR. Figures are for limited companies on unregulated agreements and exclude VAT and fees. Sole traders and partnerships borrowing £25,000 or less may be regulated and are quoted differently.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 20 Google reviews
Tell us what you need. We will call you within 24 business hours.
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
