
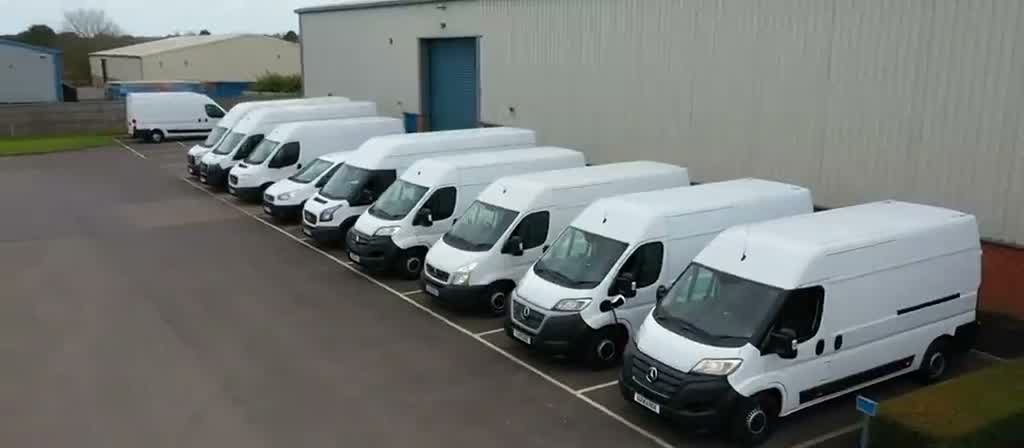
Medium van finance
The size most trades actually need, big enough for a full day of materials, small enough for a residential street, funded new or used.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersWhole-of-market panel, not one bank
- 5.0 from 19 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes. Medium vans are the single strongest category in the light commercial market and lenders like them for exactly that reason: the used demand behind a Transit Custom, Vivaro or Trafic is deep enough that a funder is confident about recovering value. That confidence usually translates into a wider choice of lenders and a smoother decision than you get on specialist bodywork. Used examples are readily fundable. Where people come unstuck is ex-fleet mileage, a three-year-old van with very high motorway miles can be valued well below the asking price, and the funder lends against its figure, not the advert.
Who finances this
Plumbing and heating firms, kitchen fitters, alarm and CCTV installers, and small logistics operators who have outgrown a compact van but do not want the parking and fuel penalty of a Sprinter. Commonly a limited company running two to five vehicles that replaces one van a year on a rolling basis. The trigger is often a van hitting the mileage where the warranty has run out and the first big bill has landed.
How lenders see it
This is the easiest part of the LCV market to place, so the conversation shifts from whether anyone will fund it to which structure serves you best. Almost the whole panel writes medium vans, including funders who are fussy elsewhere. Limited companies with two or more sets of accounts have the run of the market; sole traders are fine; new starts are workable with a deposit or a homeowner behind the deal. The real underwriting attention goes on mileage and provenance. Ex-rental and ex-parcel-network stock is discounted because of how it has been driven. A dealer invoice is expected. Applications that fail here are usually private purchases, imported vehicles with no UK service history, or a valuation that will not stretch to the price agreed.
Buying used
Yes, and this is the used category lenders are most comfortable with, several-year-old medium vans are funded routinely, with mileage mattering more than age.
Also in van and light commercial finance
See everything we fund in van and light commercial finance →
Van buying guides
We are a broker, not a dealer. We have no stake in which van you choose. These are written on that basis.
The van is one cost
Flowzo covers fuel, wages and the wait for customers to pay, working capital rather than the vehicle itself.
Machines we have funded
Typically £37,030–£54,400 + VAT to buy. New Ford Transit Custom SWB and LWB panel van, on-the-road price across Trend to Trail trims.Checked 2026-10-18.
| Ford Transit Custom L2H1 | Medium panel van, the trade default |
|---|---|
| Vauxhall Vivaro L2H1 | Value medium van for fleets |
| Renault Trafic LL30 | Long medium van for tools and stock |
| Toyota Proace Medium | Medium van with long warranty cover |
| Nissan Primastar L2H1 | Medium van for mixed trade work |
| Volkswagen Transporter T6.1 | Medium van with strong residuals |
| Peugeot Expert Professional | Medium van with low load height |
| Citroen Dispatch XL | Long medium van for courier work |
| Fiat Scudo | Medium van for light commercial use |
| Ford Transit Custom Trail | Medium van with all-wheel traction |
What counts as a medium van?
Roughly the Transit Custom class, bigger than a Caddy or Combo, smaller than a Sprinter or Boxer. Usually around three metres of load length in short wheelbase form, a payload around a tonne, and a height that still clears most multi-storey car parks. It is the default choice for most trades.
Is high mileage a problem for van finance?
It is a valuation issue more than a credit one. A lender will lend against what the van is worth, and very high mileage pulls that figure down. If the price you have agreed is above the funder valuation you may need to cover the gap. We flag this before you commit to a deposit.
Can I finance an ex-fleet or ex-rental van?
Yes, and they are often good value with full service history. Lenders apply a discount to ex-rental and parcel-network stock because of how hard those vans work, so expect the valuation to be conservative. Buying from a reputable remarketing dealer rather than a raw auction makes it far easier to place.
Should I choose hire purchase or a lease for a medium van?
It depends on whether you keep vans long term. Hire purchase suits operators who run a van until it is worn out and want to own it. A lease can suit businesses that change vehicles on a cycle and want a predictable handover. We will talk through the trade-offs for how you actually work.
Can I add signwriting and racking to the finance?
Often yes, if it is invoiced as part of the supply and forms part of the vehicle being funded. Racking and livery add no resale value, so lenders look at the total against the van worth. Getting one combined invoice from the supplier makes this much simpler.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Illustrative only, not a quote, a flat rate is not an APR, so the APR on a given agreement will be higher. VAT and fees excluded.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 19 Google reviews
Thinking about medium van finance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
