
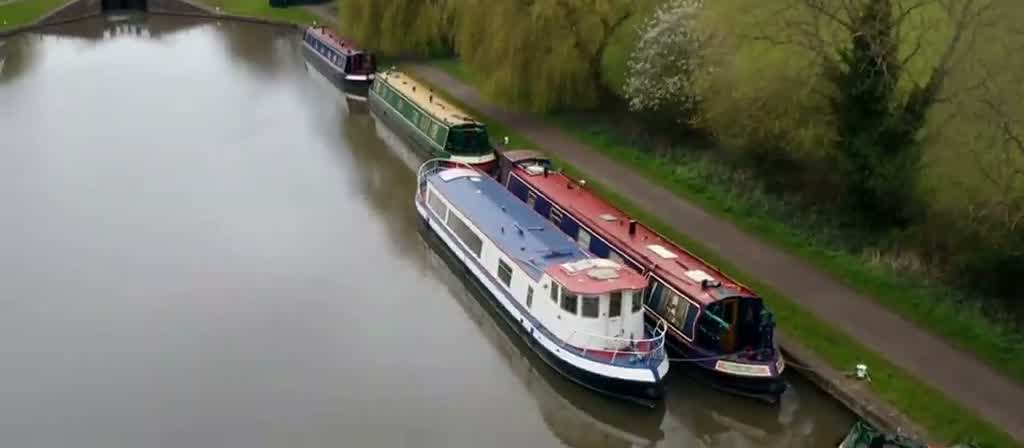
Narrowboat finance
Funding for steel canal boats bought for weekends, extended cruising or as a home, placed with lenders who understand inland waterways craft.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersWhole-of-market panel, not one bank
- 5.0 from 19 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes. A narrowboat is funded as a marine asset, normally on hire purchase or a marine loan secured against the boat itself and not against any mooring. Used boats are very fundable, almost the whole British market is second-hand, and a sound steel hull with recent blacking and a current Boat Safety Scheme certificate places without much difficulty. What catches people out is title. There is no V5 for a boat, so ownership has to be evidenced through the chain of bills of sale, Small Ships Register or Part 1 registration, and any marine mortgage still recorded against the hull must be cleared on completion.
Who finances this
Typically a buyer in their fifties or sixties moving from hire holidays into ownership, or a younger buyer priced out of bricks and mortar who wants a residential berth on the Leeds and Liverpool or the Trent. The trigger is usually a specific boat found at a brokerage with a holding payment made and a survey booked. Company directors buying personally are common, as are couples putting house sale proceeds towards part of the purchase.
How lenders see it
Marine sits outside the appetite of most mainstream asset funders, so placement is the whole job here. A narrowboat needs a funder comfortable with a steel hull carrying no registration document, which in practice means an out-of-water survey, hull thickness readings and a documented chain of ownership before drawdown. Where the boat is bought by an individual for leisure or residential use rather than through a trading business, the agreement may be regulated, and that narrows the panel again. Moorings are excluded from the asset: the berth is a separate licence with the marina or navigation authority, on its own contract, and cannot be rolled into the boat agreement.
Buying used
Yes, the market is overwhelmingly second-hand, and hulls of thirty or forty years are routinely funded where the survey and thickness readings support it.
Also in boat and marine finance
See everything we fund in boat and marine finance →
Machines we have funded
| Collingwood 57ft semi-trad | Steel canal cruiser |
|---|---|
| Reeves 60ft cruiser stern | Steel narrowboat hull and fit-out |
| Aqualine Canterbury 60ft | Widebeam canal boat |
| Aintree Boats sailaway shell | Bare steel shell for owner fit-out |
| Tyler-Wilson 62ft shell | Traditional stern narrowboat shell |
| Beta Marine BD3 43hp | Inland waterways diesel engine |
| Nanni N4.38 marine diesel | Canal boat propulsion engine |
| Barnowl Narrowboats fit-out | Bespoke joinery and interior build |
| Elton Moss 57ft traditional stern | Steel narrowboat for continuous cruising |
| Victron Energy lithium system | Onboard battery and inverter package |
Can I finance a narrowboat I intend to live on?
Often yes, though residential use narrows the panel. Funders want to see a mooring with residential consent or a continuous cruising plan, and they treat the boat as your home rather than a toy, so income evidence matters more. The berth itself is never part of the agreement.
Do I need a survey before finance is agreed?
In nearly all cases yes. A marine lender will want an independent out-of-water survey with hull thickness readings taken at several points. The report tells the funder whether the steel is sound and gives them something to value against, since there is no trade guide for a one-off boat.
Can the mooring be included in the finance?
No. A mooring is a licence or a berthing contract with the marina or navigation authority, not an owned asset, so it cannot be funded alongside the boat. Budget for the berth, the licence and winter blacking separately from the boat agreement. Marinas quote berthing annually and the navigation authority sets the licence separately again.
Is a part-fitted sailaway fundable?
Sometimes, and it depends on the builder. A shell from an established fabricator with a staged build contract can be placed, but a half-finished owner project with no paperwork is difficult because the funder cannot easily value or resell it. Talk to us before you commit.
What happens if the seller still has finance on the boat?
It has to be settled at completion. Because there is no vehicle-style register, we establish the outstanding balance with the existing funder, get a settlement figure in writing and pay it from the drawdown so you receive clear title with the bill of sale. Never rely on a verbal assurance from a seller that nothing is outstanding.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Illustrative only, not a quote, a flat rate is not an APR, so the APR on a given agreement will be higher. VAT and fees excluded.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 19 Google reviews
Thinking about narrowboat finance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
