
River cruiser finance
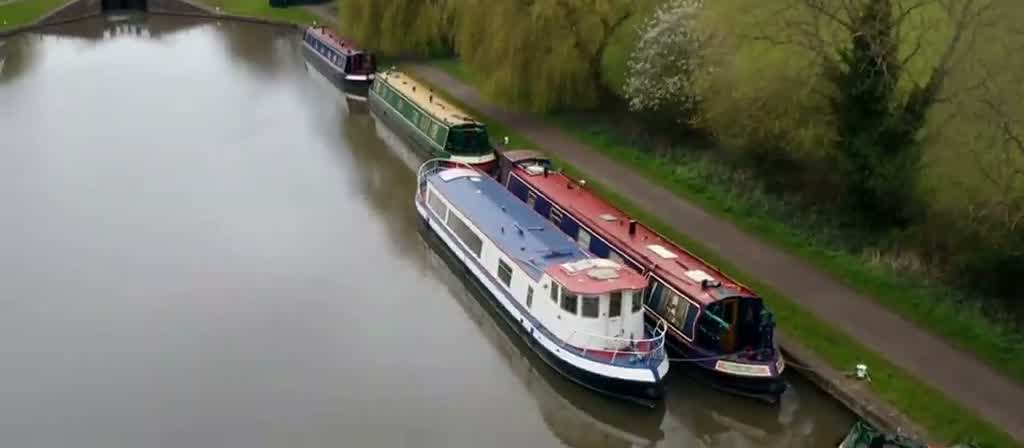
Finance for glass fibre inland cruisers on the Thames, Great Ouse and Norfolk Broads, arranged with funders who price a river boat properly.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersWhole-of-market panel, not one bank
- 5.0 from 19 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes. River cruisers are funded as leisure marine assets, usually on hire purchase or a marine loan taken against the craft. Second-hand boats make up nearly the entire market, and funders will consider hulls built decades ago provided the survey reads well and the engine has a service history. The point buyers miss is that a glass fibre hull is judged on osmosis, deck delamination and stringer condition rather than on age or hours, so the surveyor shapes what a lender is prepared to advance against. Small Ships Register details and a valid Boat Safety Scheme certificate also need to be in order.
Who finances this
Usually a family or a retired couple on the Thames or the Broads stepping up from a syndicate share or a hire week, buying through a brokerage at Shepperton, Brundall or Ely. The trigger is often retirement, a move to a riverside house, or the end of a shared ownership arrangement. Buyers frequently want the boat funded on its own rather than borrowing further against the home, and want the purchase settled before the season starts.
How lenders see it
Volume asset funders write almost no marine business, so an inland cruiser goes to the handful of lenders who genuinely operate in this space. Those funders will want an independent marine survey, evidence that the vendor owns the craft outright, and confirmation that nothing is registered against the hull. Because the buyer is nearly always an individual buying for pleasure, the agreement is frequently regulated, which rules out commercial-only panels immediately. Berthing is a separate matter again, the marina contract, the navigation authority licence and winter hardstanding are all outside the boat agreement, and a buyer who has budgeted only for the boat gets a surprise in the first autumn.
Buying used
Yes, used dominates this class, and well-kept hulls from the 1980s onwards are commonly funded when the survey and engine hours stack up.
Also in boat and marine finance
See everything we fund in boat and marine finance →
Machines we have funded
| Broom 35 Coupe | Aft-cabin river cruiser |
|---|---|
| Broom 430 | Inland and coastal aft cabin cruiser |
| Haines 32 Sedan | Sedan-style river cruiser |
| Haines 400 Aft Cabin | Broads and river cruising boat |
| Sheerline 950 | British-built canal and river cruiser |
| Sealine S330 sports cruiser | Petrol or diesel sports cruiser |
| Bavaria Sport 300 | Sports cruiser for rivers and estuaries |
| Fairline Targa 34 | Sports cruiser with aft cabin |
| Nanni T4.200 diesel | Inboard diesel for river cruisers |
| Volvo Penta D3-220 shaft drive | Inboard diesel and sterndrive package |
How old a river cruiser will a lender consider?
Older than most people expect. Glass fibre does not date in the way a vehicle does, so condition governs the decision rather than the year. A cared-for hull with a recent engine overhaul often places more easily than a newer boat that has sat unused on a mud berth for several seasons.
Does osmosis stop the boat being funded?
Not automatically. Blistering is common on older GRP and a surveyor will grade how far it has gone. Light cosmetic blistering is usually accepted, while structural moisture or a failed previous treatment gives a funder reason to pause until remedial work is quoted and done.
Can I buy privately rather than through a brokerage?
Yes, though private sales take longer to fund. A broker holds client money and prepares the bill of sale, whereas a private deal means we have to build the ownership trail ourselves from receipts, registration entries and any earlier finance settlement letters before funds can be released.
Do I need the boat registered before finance completes?
Registration on the Small Ships Register is quick and inexpensive, and most funders want it or Part 1 registration in place at or shortly after completion. It gives the lender something to tie the agreement to, which matters on a craft with no equivalent of a logbook.
Can I finance a boat that is already on a Broads hire fleet?
Sometimes. An ex-hire boat is usually well maintained but heavily used, and the funder will want the operator to confirm the hours and the hull history. If the boat is being bought to keep earning, the deal is assessed on the charter income rather than as a leisure purchase.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Illustrative only, not a quote, a flat rate is not an APR, so the APR on a given agreement will be higher. VAT and fees excluded.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 19 Google reviews
Thinking about river cruiser finance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
