Customer situation
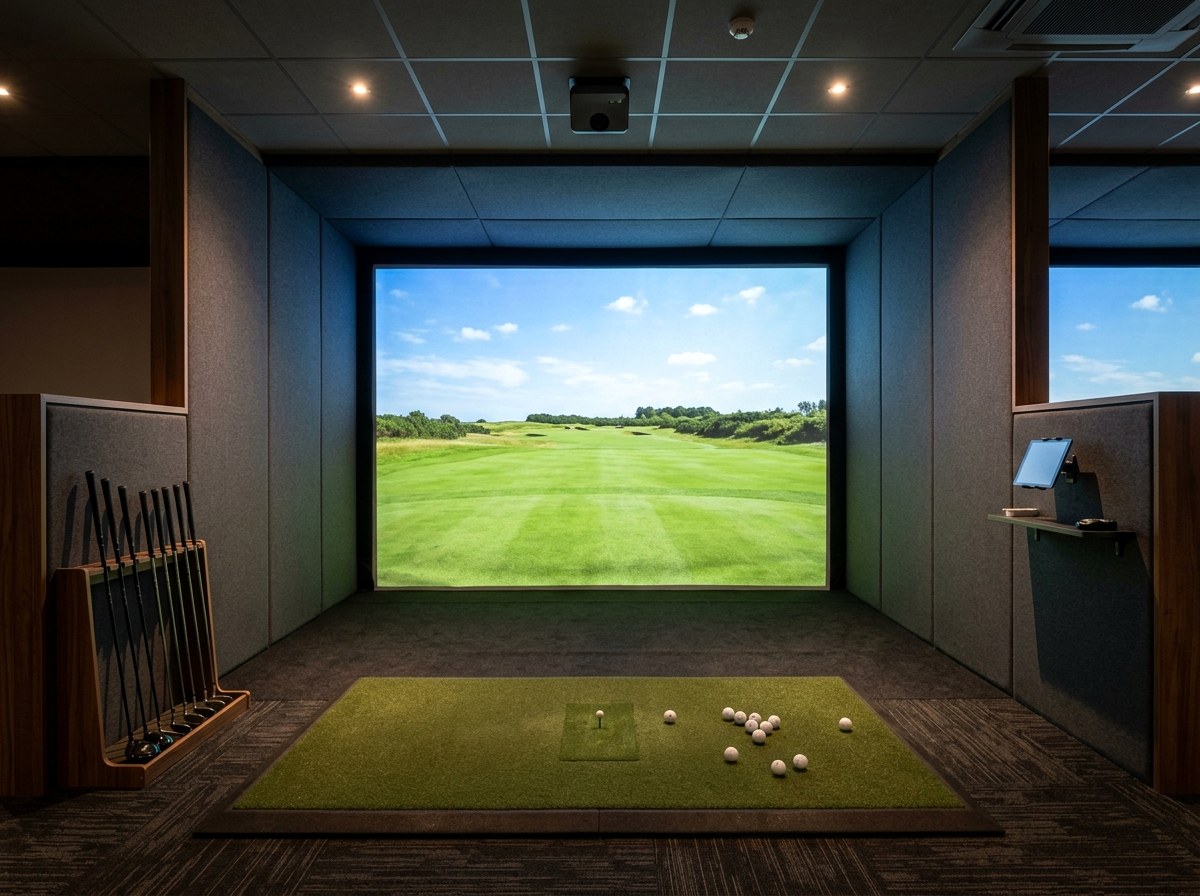
A fit-out company formed earlier the same year, buying a commercial golf simulator — a Foresight Falcon launch monitor, a full-size screen kit, a projector and the software to run it. Just under £21,510 including VAT.
The challenge
Eight months of trading and no filed accounts. On paper that is the profile most people assume is unfundable, and most enquiries like it are turned away before anyone looks properly.
With no accounts there is no payment history to score and no track record to lean on. Something has to carry the risk, and on a new business that is usually the director personally — which means a guarantee is only worth what stands behind it. A director who owns their home is a materially different proposition to one who does not. It is not about wealth; it is that the guarantee has substance. On a new-start application it is often the single factor that moves a decline to an approval.
Put plainly, the test is one of two things: twelve months of trading behind the business, or a homeowner applicant with experience in the sector they are working in. At eight months old this one did not clear the first, so it had to clear the second. Neither limb is a formality, and a new start with neither is not a deal yet, whatever the asset.
There was a second point against it. A golf simulator is not a van or an excavator. It has no auction history a lender can look up and a narrower resale market, so it needs a funder comfortable pricing leisure equipment rather than one working from a vehicle schedule.
What we did
The business contributed £6,000 against a purchase of £21,510 — around 28%, materially more than an established company with three years of accounts would typically be asked for. That is the cost of being new: a bigger stake, which reduces the funder’s exposure and gives it a reason to say yes. The balance went over four years on hire purchase.
It is worth being plain about one feature of hire purchase that catches people out. Under HP the equipment is hired until the final payment, and a small option-to-purchase fee at the end is what transfers ownership. It is a modest sum, but if it is not paid the agreement ends without the asset becoming yours — better known on day one than in month forty-eight.
Key outcome
A company in its first year of trading took delivery of a revenue-generating asset it would otherwise have waited a year for, on a four-year agreement with a deposit it chose rather than one imposed on it.
“New businesses get told asset finance is closed to them until they have filed accounts. That is not quite right. What changes is what the funder needs to see — usually a homeowner director and a real deposit. Being told no by one lender is not the same as the answer being no.”
— Conor, CW Asset Finance
Every application is assessed on its own merits and all finance is subject to status and lender approval. This is one client’s outcome and is not a guide to what any other business will be offered.
Explore golf and groundcare finance →