
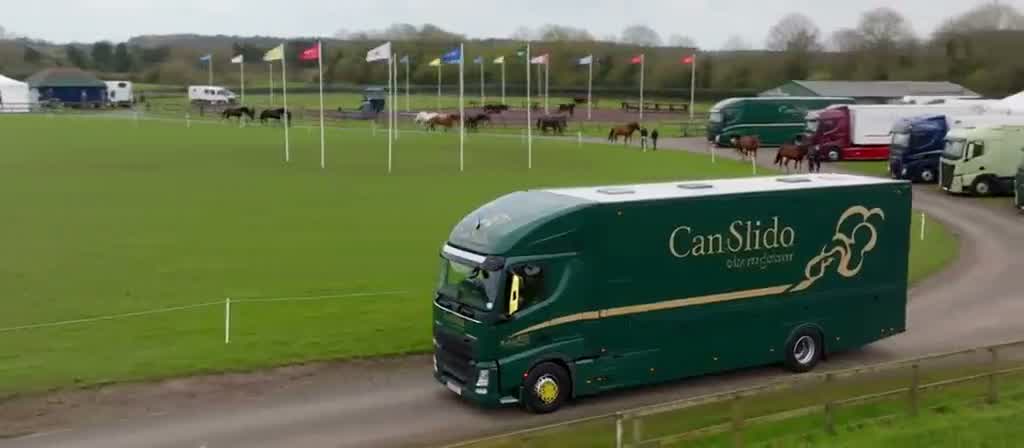
horsebox refinance
If your box is sitting in the yard paid for, the value in it can often be released without selling the vehicle or missing a season.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersA panel of lenders, not one bank
- 5.0 from 20 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes, where you own the box outright and it can be identified and valued. The usual mechanism is a sale and hire purchase back: a funder buys the vehicle from you, pays you, and hires it back under a new agreement while you carry on using it. If an existing agreement is running, some funders will settle it and replace it. Businesses refinancing a working box are on unregulated terms with a wider panel. Private owners raising money against a personally used box are in regulated consumer lending, where fewer funders operate.
Who finances this
Yards releasing cash before the season to buy horses, cover feed and bedding contracts or fund an arena surface. Riders who bought a box outright with a windfall and now want some of that money back. Transport operators smoothing cash flow between contracts. The trigger is almost always a need for capital somewhere else in the business, with a valuable asset sitting on the yard doing nothing financially.
How lenders see it
Ownership has to be clean. The funder will want the V5C in your name, the original purchase invoice and a check confirming nothing is registered against the vehicle, because they cannot take security behind another lender. Valuation is on current condition, which for a horsebox means the floor, the ramp, the plating history and the state of the living area. Expect photographs and possibly an independent inspection. The regulated distinction is sharper on refinance than on a purchase. Raising money against a box used for personal competition is consumer lending, subject to affordability checks and questions about the purpose of the funds. A livery yard, transporter or professional producer refinancing a genuinely commercial vehicle is on unregulated business terms, which is both quicker and open to more funders.
Buying used
Yes, refinance always involves a used asset, and older boxes qualify where condition and plating history support a defensible valuation.
Also in horsebox and horse trailer finance
See everything we fund in horsebox and horse trailer finance →
Machines we have funded
| Oakley 7.5t horseboxes | Owned British coachbuilt horsebox |
|---|---|
| Oakley HGV horseboxes | Owned HGV horsebox |
| Equi-Trek Sonic | Owned 3.5 tonne horsebox |
| Equi-Trek Eventa L | Owned 7.5 tonne horsebox |
| KPH 18t horseboxes | Owned HGV horsebox |
| Bloomfields Prima | Owned lightweight horsebox |
| Whittaker Horseboxes | Owned bespoke horsebox |
| Bockmann Big Horse | Owned German horse truck |
| Theault Proteo | Owned French horsebox |
| Ifor Williams HB511 | Owned two horse trailer |
Do I keep using the box during the agreement?
Yes. You continue to use it exactly as before, with obligations to keep it insured, maintained and within the agreed territory. What changes is that the funder holds title until the agreement ends, so you cannot sell the box without settling first. Day to day use, competing and travelling are unaffected.
How recently must I have bought it?
Some funders have a window after purchase within which a sale and hire purchase back is straightforward, and others will consider vehicles owned for years. What matters most is that you can evidence ownership with the V5C and the original invoice. If the purchase was a long time ago and the invoice is lost, tell us early so we can approach it differently.
Can I refinance a box that still has finance on it?
Not as a sale and hire purchase back, because the vehicle is already secured. The alternative is for a new funder to settle the existing balance and write a fresh agreement, which requires a settlement figure from your current lender. Whether that improves your position depends on the numbers and any settlement implications.
Is a valuation always required?
Not always, but expect one on older or higher value boxes. Funders may work from trade data and photographs where the vehicle is a mainstream model in obvious condition. On a bespoke box, a rebodied vehicle or one of significant age, an independent inspection is the normal route to agreeing a figure everyone accepts.
Can the money be used for anything?
On a business agreement, funds are generally used for business purposes and the funder will ask what for. On a regulated consumer agreement the questions are more detailed, because affordability and purpose assessments are a regulatory requirement. Be straightforward about your intentions, vague answers slow applications down more than honest ones.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Total repayable about £,
Illustrative only, not a quote. Flat rates are indicative, subject to status and are not an APR. Figures are for limited companies on unregulated agreements and exclude VAT and fees. Sole traders and partnerships borrowing £25,000 or less may be regulated and are quoted differently.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 20 Google reviews
Thinking about horsebox refinance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
