
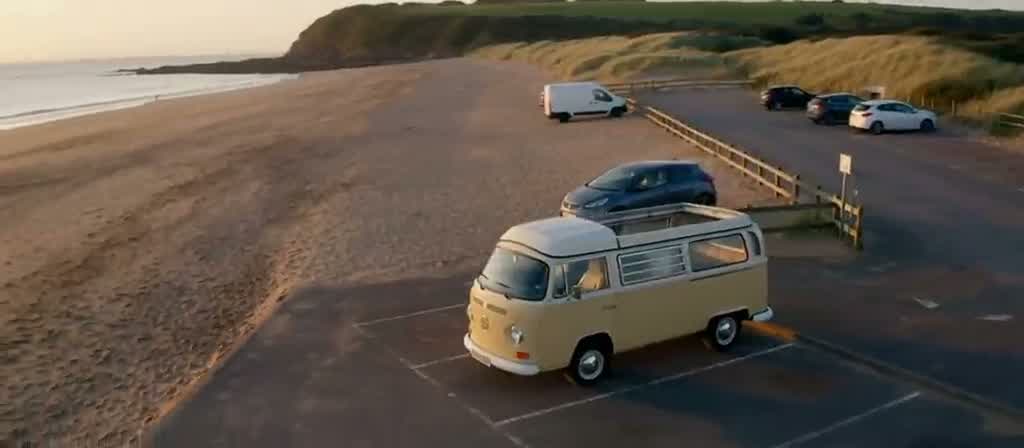
campervan finance
The question that decides a campervan application is never the price. It is whether the V5C says motor caravan and who did the conversion work.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersA panel of lenders, not one bank
- 5.0 from 20 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes, with one qualifier that decides everything: how the vehicle is registered and who converted it. A factory campervan or one built by an established professional converter, registered as a motor caravan with documentation to match, is ordinary business for a funder. A van someone fitted out themselves is a much harder proposition. An individual buying for weekends away will normally be on a regulated consumer agreement; a surf school or rental operator buying the same van is on unregulated business finance. Used campervans fund freely. The usual stumbling block is a seller who describes a van as a campervan when the logbook still says panel van.
Who finances this
This is the youngest buyer group in the leisure market by some distance. Couples in their thirties, climbers, surfers, dog owners and weekend cyclists who want something they can park on a normal drive and use on a Friday night without planning a trip around it. The trigger is often a first proper job with a company car freed up, or a decision not to replace a second car. A fair number have hired one for a week and come back convinced.
How lenders see it
Two things drive the decision here and price is not one of them. First, registration: if the V5C body type reads motor caravan, the funder is looking at a leisure vehicle with leisure values. If it reads panel van, the funder values a panel van however nicely it is trimmed inside, and the numbers fall away. Second, provenance of the conversion, a named converter with an invoice, a build spec and a gas safety certificate gives the desk something to underwrite. Then there is the buyer. Private ownership means a regulated consumer credit agreement and an authorised consumer lender; a hire fleet or a business vehicle is unregulated and goes elsewhere. Private sales are frequent in this market and most funders will want the seller’s title and the absence of outstanding finance evidenced before releasing anything.
Buying used
Yes, used campervans are funded readily and demand for good ones is strong, with vehicles up to around a decade old presenting no real difficulty where the conversion is documented.
Also in motorhome and campervan finance
See everything we fund in motorhome and campervan finance →
Machines we have funded
| Volkswagen California Ocean T6.1 | Pop-top VW campervan |
|---|---|
| Volkswagen Grand California 600 | Factory built large campervan |
| Westfalia Kepler One | Panel van campervan conversion |
| Adria Twin Supreme 640 SGX | Panel van campervan |
| Swift Select 184 | British built campervan |
| Auto-Trail Expedition 67 | Compact British campervan |
| Chausson V697 campervan | French panel van conversion |
| Hymer Grand Canyon S | Four wheel drive capable campervan |
| Ford Transit Custom Nugget | Pop-top Ford based campervan |
| Knaus BoxStar 600 | Panel van campervan conversion |
What does registering a van as a motor caravan actually change?
For funding purposes it changes what the vehicle is. Body type on the V5C is the first thing an underwriter reads, and motor caravan puts the vehicle into the leisure category where values hold up. A van still registered as a panel van gets valued as one, regardless of the bed, hob and pop-top inside it. The DVLA criteria for reclassification have tightened, so check the current position rather than assuming.
Can I fund a campervan for use in a hire business?
Yes, and it is a different product. A hire fleet is a business asset, so the agreement is unregulated business finance rather than consumer credit, and the funder will want to see the operating plan, the insurance basis and how seasonal the income is. Most van hire income is concentrated into a few warm months, and a sensible structure allows for that.
Is a pop-top roof a problem for a lender?
An elevating roof fitted by a recognised installer is entirely normal and does not cause difficulty. What a funder wants to avoid is a roof cut by an unknown hand with no paperwork, because that is a structural alteration to the vehicle and there is no way to assess how well it was done. Keep the installation invoice with the vehicle’s documents.
Does a campervan need a gas safety certificate for finance?
Not always, but produce one if you have it. On any conversion with a fitted gas system a current certificate tells the underwriter the installation was done properly and inspected, which quietly answers several questions about the quality of the whole build. On older vehicles it can be the difference between a yes and a request for more information.
Are day vans treated the same as campervans?
No, and it trips people up. A day van has seating, trim and often a nice audio system but no cooking, sleeping or washing facilities, so it stays a van in the funder’s eyes and is valued accordingly. If you want the vehicle treated as a leisure asset it needs the habitation features and the registration to go with them.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Total repayable about £,
Illustrative only, not a quote. Flat rates are indicative, subject to status and are not an APR. Figures are for limited companies on unregulated agreements and exclude VAT and fees. Sole traders and partnerships borrowing £25,000 or less may be regulated and are quoted differently.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 20 Google reviews
Thinking about campervan finance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
