
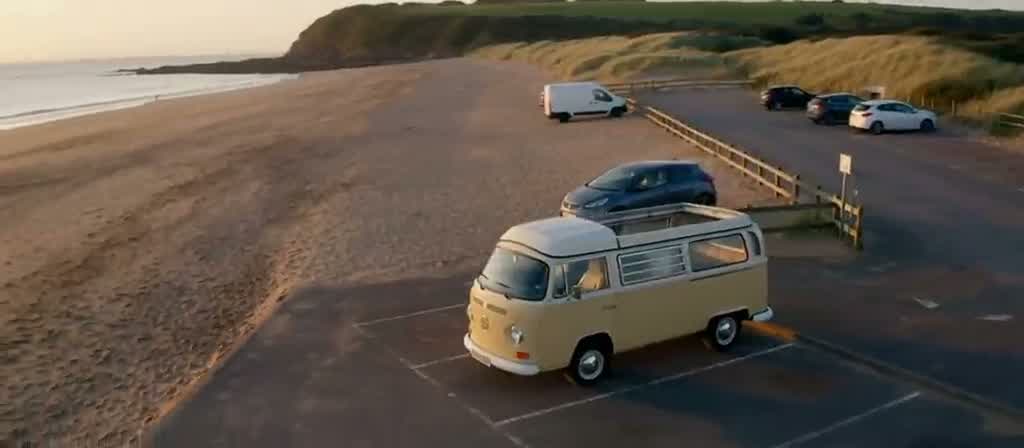
panel van conversion finance
Finance for factory built panel van campers, the high roof, fixed bodied vans produced in volume by European manufacturers rather than converted one at a time.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersA panel of lenders, not one bank
- 5.0 from 20 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes. Factory panel van conversions are among the most straightforward leisure vehicles to fund. Because they are series produced by established manufacturers on Ducato, Sprinter or Crafter bases, there is published trade data behind them and an underwriter can put a reliable value on the vehicle. Dealer purchases are simplest. Buyers who want the van for holidays and weekends will usually be looking at a regulated consumer credit agreement, while a van going into a hire fleet, a site business or a sole trader’s name for work use is funded as unregulated business finance instead.
Who finances this
Often a retired or semi retired couple downsizing from a coachbuilt motorhome because a van fits on the drive and through a height barrier. Also younger buyers who want something they can use as a daily vehicle rather than a second one that sits idle eleven months of the year. The trigger tends to be a change in circumstances, retirement, a house move with a shorter driveway, or the end of the last vehicle’s warranty.
How lenders see it
Series built vans sit in a sweet spot. The manufacturer is recognised, the layout codes are standard and the resale market is active, so funders are comfortable and the panel of available lenders is wide. Where it gets more involved is purpose and seller. If an individual is buying for private leisure use the agreement is likely to be regulated consumer credit, which limits you to funders who hold the right permissions but brings consumer protections with it. A business buying the same van for staff accommodation, event work or hire has an unregulated agreement and a broader choice of funder. Buying from a private seller rather than a dealer also cuts the panel down sharply, and the ones that remain ask for the invoice, the chassis number and written confirmation there is no finance outstanding.
Buying used
Yes, used panel van conversions fund easily, and vehicles from the last decade or so are traded and funded every week.
Also in motorhome and campervan finance
See everything we fund in motorhome and campervan finance →
Machines we have funded
| Adria Twin Supreme 640 SGX | Panel van conversion camper |
|---|---|
| Adria Twin Axess 600 SP | Compact panel van conversion |
| Chausson V697 campervan | French panel van conversion |
| Auto-Trail Expedition 66 | British panel van conversion |
| Burstner Campeo C 640 | German panel van camper |
| Hymer Grand Canyon S | Premium panel van conversion |
| Hymer Free 600 Campus | Compact panel van camper |
| Swift Select 174 | British built van conversion |
| Knaus BoxLife 600 MQ | Rear garage panel van conversion |
| Westfalia Columbus 640 E | Panel van conversion with fixed beds |
How is this different from financing a coachbuilt?
The body is the main difference. A panel van keeps the original steel shell, so there is no separate coachbuilt structure to inspect and fewer damp related worries. Funders often find them easier to value as a result. The trade off is that the underlying van is a commercial vehicle, so mileage and service history carry more weight in the decision.
Can I add an awning, solar or a bike rack to the agreement?
Often yes, provided the extras are listed on the same supplying invoice and fitted before delivery. Items bought separately after the vehicle has been funded generally cannot be added later, because the agreement is already drawn against a specified asset. It is worth deciding on extras before the paperwork is issued rather than afterwards.
Is a van conversion classed as a motorhome for finance?
Usually yes. What the V5C says matters more than the marketing name, a vehicle registered as a motor caravan is assessed as a leisure vehicle, while one still registered as a panel van may be looked at on commercial vehicle terms. Tell us how it is registered at the outset so the enquiry is placed correctly.
Does a high mileage van put funders off?
It can, but base vehicle diesels used for leisure often cover modest annual mileage, and underwriters judge the figure against the age. A full service history and a clean MOT record will do more to reassure a funder than a low reading alone. Where mileage is high, evidence of cambelt and servicing work matters.
Can my limited company buy one?
Yes, where there is a genuine business use such as site work, event support or hire. That makes it unregulated business finance, so a wider panel of funders can consider it. You should take your own tax advice on how the vehicle is treated, because the rules around private use of a company owned vehicle are a matter for your accountant.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Total repayable about £,
Illustrative only, not a quote. Flat rates are indicative, subject to status and are not an APR. Figures are for limited companies on unregulated agreements and exclude VAT and fees. Sole traders and partnerships borrowing £25,000 or less may be regulated and are quoted differently.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 20 Google reviews
Thinking about panel van conversion finance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
