
Financing a second van or machine while you are still paying for the first
Can you finance a second van, truck or machine while the first is still on finance? Yes. How lenders weigh the first agreement, and when one facility is better.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersA panel of lenders, not one bank
- 5.0 from 20 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes. Having one agreement running does not stop a business taking a second, and a clean payment record on the first is often the strongest thing in the application. The lender looks at whether the business can carry both payments, so it wants recent bank statements and the work the second asset is for. Your existing lender may add the second to a facility on simpler paperwork, or another lender on our panel may take it, which spreads the exposure.
What the lender looks at
- Both payments together against what comes into the account. Recent bank statements matter more than last year’s accounts here.
- How the first agreement has run. A year of payments on time is real evidence.
- Why you need the second: a new contract, a second crew, a driver taken on. Show the work that pays for it.
- The asset itself. Vans, trucks and plant hold their value, which makes a second agreement easier to place than one for a soft asset.
- Your personal credit and, on a younger business, a personal guarantee.
Same lender or a different one
Going back to the lender that funded the first is often quickest. They know how you pay, and some will add the second asset under the same master agreement with lighter paperwork. The catch is that every lender caps how much it will lend to one business, so the second or third asset may push you past their limit.
A different lender looks at you fresh and sees the first agreement on your credit file and in your bank statements. That is not a problem in itself; it is just one more commitment it weighs. Spreading agreements across two lenders also leaves room with each for the next asset.
When one agreement for several assets makes sense
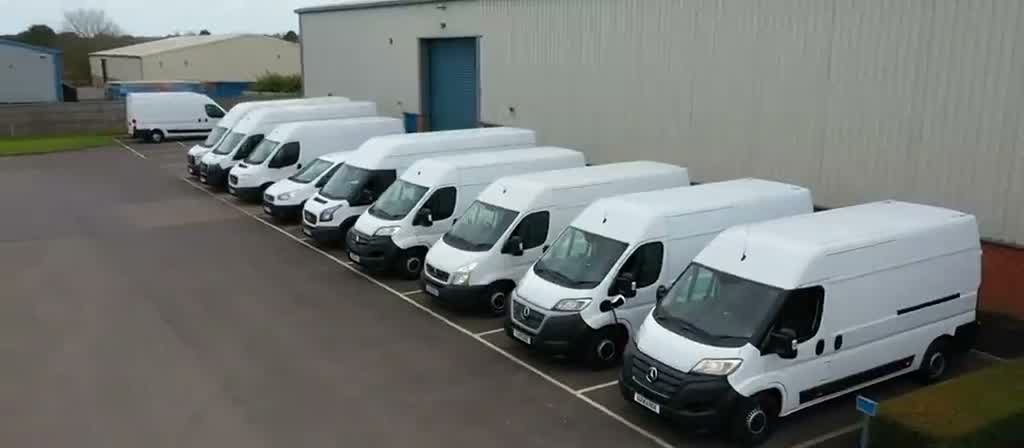
If you are buying two or more at once, putting them on one agreement means one credit check, one set of paperwork and one payment date. Growing fleets often move to a facility, where the lender approves a limit and each new van or machine is drawn against it. Van fleet finance.
Things that make it harder
- Arrears or a missed payment on the first agreement, however small.
- Bank statements that show the account going overdrawn every month.
- Asking for a second asset in the first few months of a brand new business, before there is any trading to show.
- Using the second agreement to cover payments on the first. Lenders spot it, and it is a decline.
What it costs a month
On the representative example used across this site, borrowing £25,000 over 48 months at 5.15% flat is about £628 a month, £30,150 repayable in total. Illustration only, not a quote. VAT and fees excluded, and subject to status. Two assets of that size would be about £1,256 a month together, which is the figure a lender checks against your bank statements.
A deal like this
We funded two Land Rover Defender Hard Tops for a construction company on one four year hire purchase, with no deposit and payout eight days after the file was opened. It is one example, not a promise of the same approval.
Read the write-up
Related guides

Written and reviewed by Conor Hull, founder of CW Asset Finance.
Last reviewed 17 November 2026. About Conor
An independent asset finance broker in Tadcaster, North Yorkshire, working with more than 60 lenders. When you ring, Conor answers, and he speaks to the underwriter on your proposal himself.
CW Asset Finance is a trading name of Conor William Hull, an Appointed Representative (FRN 1031964) of Rural Finance Limited, authorised and regulated by the Financial Conduct Authority (FRN 630701). We are a credit broker, not a lender.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Total repayable about £,
Illustrative only, not a quote. Flat rates are indicative, subject to status and are not an APR. Figures are for limited companies on unregulated agreements and exclude VAT and fees. Sole traders and partnerships borrowing £25,000 or less may be regulated and are quoted differently.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 20 Google reviews
Tell us what you need. We will call you within 24 business hours.
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
