The situation
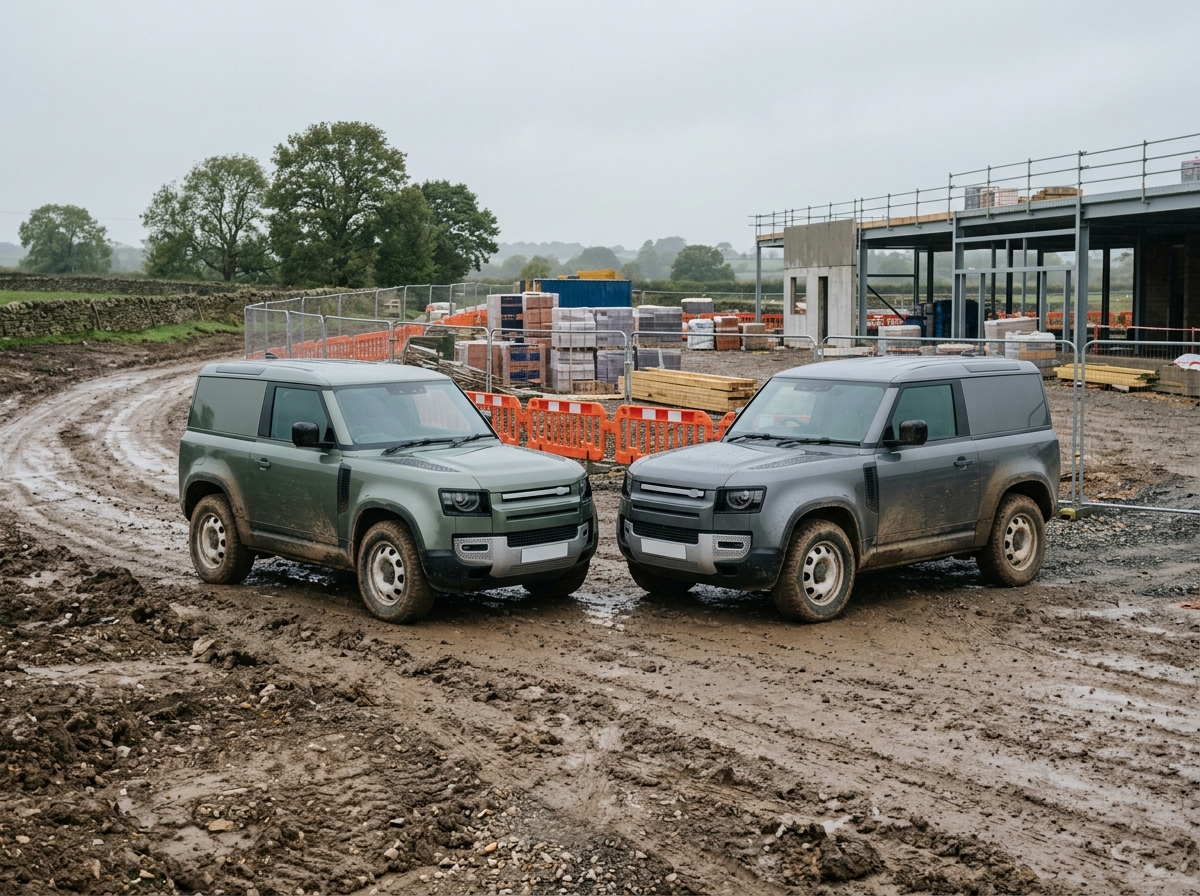
A construction projects company funding two Land Rover Defender Hard Tops together — just under £103,000 on a single four-year hire purchase, with nothing put in at the start.
The challenge
The vehicles were straightforward. The part that took working out was the final payment. A balloon defers a chunk of the capital to the end of the agreement instead of spreading it across the monthly payments. Set it too high and you have built a problem for year four; set it too low and you have paid for flexibility you did not use.
What we did
Two lenders were approached and one was chosen. The agreed final payment was £60,000. That figure is a negotiation rather than a calculation: the lender is asking what the vehicles will realistically be worth in four years, because that residual is its security, while the company is asking what monthly payment its cash flow supports. Defenders hold value unusually well for a commercial vehicle, which is what made a balloon of that size defensible — the same structure against an asset that depreciates hard would not have been offered at any price.
It is worth being plain about the other side of that. The £60,000 does not disappear. At the end of the term it is settled from cash, refinanced onto a new agreement, or the vehicles are sold or handed back to cover it. A balloon suits a business with a clear view of its position four years out, and anyone considering one should decide at the outset which of those three exits they expect to take.
Key outcome
Both vehicles funded on one agreement with no deposit, a monthly commitment the business was comfortable carrying, and payout eight days after the file was opened.
“A balloon is not a discount, and any broker who sells it as one is storing up a conversation for year four. It is a way of matching the payments to what the asset is actually worth over the time you hold it — which only works if you know how you intend to settle it.”
— Conor, CW Asset Finance
Every application is assessed on its own merits and all finance is subject to status and lender approval. This is one client’s outcome and is not a guide to what any other business will be offered.
Explore commercial vehicle finance →