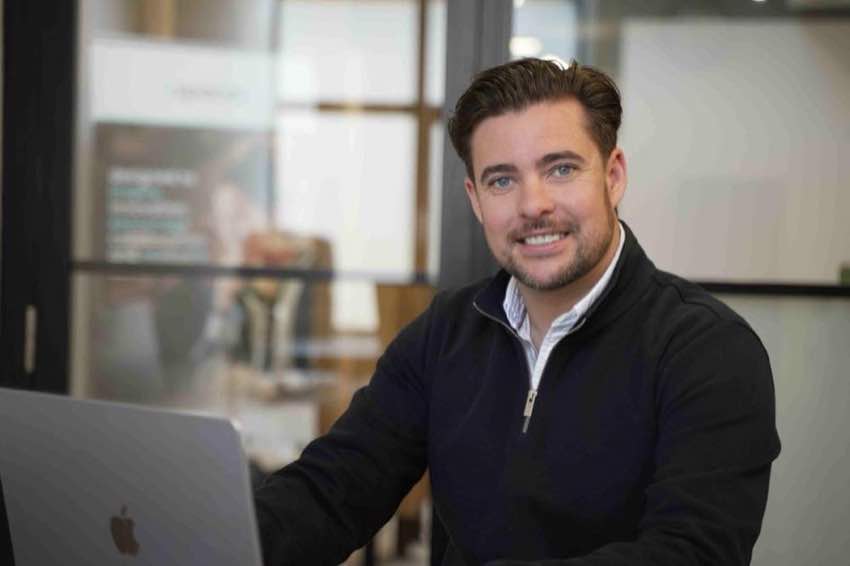
The person you will be dealing withAbout Conor Hull
CW Asset Finance is a one-person business, and that is deliberate. When you ring, I answer. When your proposal goes to a lender, I am the one speaking to the underwriter. If the answer is no, you hear it from me directly rather than from a holding email a fortnight later.
I am originally from Bangor, County Down, and my first job was on the forecourt at Sammy Mellon’s Hyundai of Bangor. That turned into fifteen years in the motor trade — which is a useful apprenticeship if you end up arranging finance for a living. You learn quickly that a customer who is keen on Tuesday has gone cold by Friday, that a unit sitting unsold costs somebody money every week, and that a finance company taking ten days to answer has effectively said no whatever it eventually says. I have been on the other side of that phone call, waiting.
I moved into asset finance and have been self-employed for all of it — four years as a self-employed broker with Harewood Asset Finance, where I specialised in golf finance and car finance, and the last seventeen months running CW Asset Finance. There has never been a salary underneath this, which concentrates the mind: I only get paid when a deal completes, so there is no percentage in stringing along a case that was never going to fly.
The golf side is a genuine specialism rather than a line on a CV — I am a keen golfer myself, which means when a club is weighing up a fleet of greens mowers, a course irrigation project or a clubhouse refit, I understand how the committee thinks about it and how the money actually moves through a season.
I have also spent time working around auctions, which is where the value of getting funding sorted before the hammer falls becomes very obvious. Bid first and arrange the money afterwards, against a settlement deadline of a few days, and you find out how unforgiving that timetable is.
The business is based in Tadcaster, North Yorkshire, and I am back in Northern Ireland roughly once a month seeing clients and dealers face to face. Not a promise to come over if something big enough turns up — an actual monthly visit.
What I am trying to do with all of it is simple enough: give businesses good finance options and a quick, reliable answer. Not the cheapest headline rate on a facility that arrives too late to be any use, and not a maybe that drags on for a fortnight. A straight answer, early, from someone who has read the deal.
15 years in the motor tradefrom a Bangor forecourt onwards — I have sat on the dealer’s side of the desk
Self-employed throughoutfour years broking with Harewood Asset Finance, then CW Asset Finance
Golf finance specialistand a keen golfer — I know how a club committee actually reaches a decision
Appointed Representativeof Rural Finance Limited, authorised and regulated by the Financial Conduct Authority. FRN 1031964. NACFB member.