
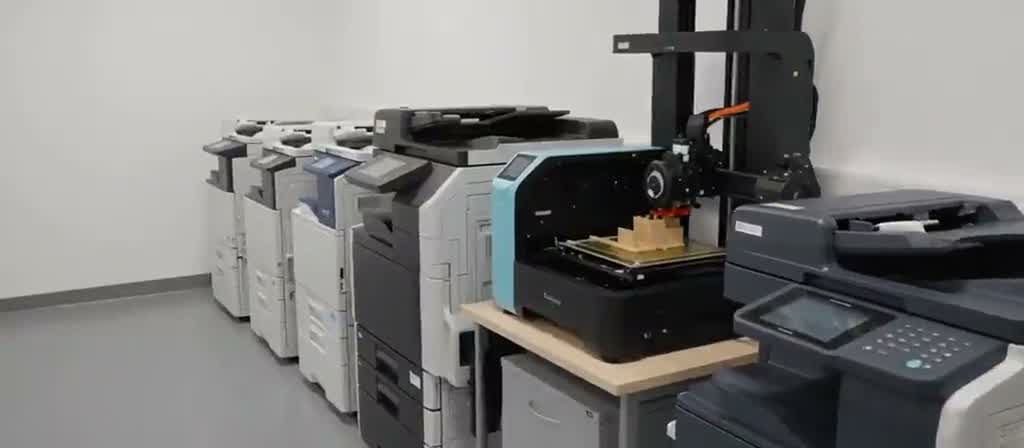
Production print finance
Fund a digital press, wide format machine or finishing line and let the work it wins pay for it over time.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersWhole-of-market panel, not one bank
- 5.0 from 19 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes, and this is the one corner of technology finance that behaves like proper hard asset lending. A production press or wide format printer is a heavy industrial machine with a real second-hand market, international dealers and verifiable click counts. Funders will lend against it with genuine confidence. Agreements are normally hire purchase or lease. Used presses are regularly funded, unlike almost everything else in IT. What surprises buyers is duty cycle: the machine’s recorded click count matters more to its value than its age, so a heavily worked press is treated differently to a lightly used one.
Who finances this
Commercial printers, in-plant print rooms, sign makers, packaging converters and direct mail houses. The trigger is usually a contract win that exceeds current capacity, a move into a new product such as short-run packaging or personalised mail, or an ageing machine whose downtime has started costing jobs. Print businesses also invest to bring work back in house that has been going to trade suppliers at a margin they would rather keep.
How lenders see it
Production print is where I stop worrying and start underwriting an asset properly. These machines are serialised, transportable by specialist hauliers, and there is an established international market for used presses with dealers who will bid on them. I can check click counts, service history and remaining life, and I know what a given model realises at resale. That means I can be more flexible on structure than I ever could with servers or laptops. What I still examine is the business: print is a competitive trade with thin margins, so I look at the contracts behind the investment and whether capacity is genuinely constrained. A machine bought speculatively into a quiet order book is the version I decline.
Buying used
Yes, genuinely. Second-hand digital presses and wide format machines are funded regularly, with click count, service history and dealer warranty driving the decision far more than the machine’s age.
Also in IT and technology finance
See everything we fund in IT and technology finance →
Machines we have funded
| Ricoh Pro C7500 | Digital colour production press |
|---|---|
| Ricoh Pro C5300s | Light production colour press |
| Konica Minolta AccurioPress C14000 | High-volume digital colour press |
| Konica Minolta AccurioPress C7100 | Production colour press for print rooms |
| Canon varioPRINT iX series | Sheet-fed inkjet production press |
| Canon imagePRESS V1000 | Sheet-fed colour production press |
| HP Latex 700W | Wide format latex printer for signage |
| Epson SureColor S series | Wide format solvent printers |
| Duplo finishing systems | Creasing, slitting and booklet making kit |
| Horizon binding and finishing systems | Binders and finishing lines for print rooms |
Purchase prices for production print: observed examples
Prices for production print advertised by UK suppliers run from £8,249 to £26,182 (checked 31 October 2026).
The examples have different capabilities and package contents. The Xerox starting price names a finishing package, while the other machines require their own specification checks. Ask for an itemised quotation and confirm VAT, consumables, installation and support.
| Machine | Asking price | Seen at |
|---|---|---|
| Konica Minolta AccurioPrint C751i Flux | £8,249; VAT not stated | shop.scriptumds.co.uk |
| Xerox PrimeLink C9065 package with booklet maker, trimmer, HCF and Adaptive CMYK+ | from £8,250; VAT not stated | shop.scriptumds.co.uk |
| Konica Minolta AccurioPress 6120 | from £26,182; VAT not stated | copytechgroup.co.uk |
Prices checked 31 October 2026 on shop.scriptumds.co.uk, copytechgroup.co.uk. These are asking prices observed on dealer and marketplace listings, shown as examples. They are not a quote or an offer of finance, and they move with the market. Check the current advert before budgeting.
How finance works on production print
The prices above are what a seller is asking. What a funder will actually do with the purchase is a separate question, and it is the one that decides whether the deal happens.
| Question | Typical answer |
|---|---|
| Term available | 12 to 72 months. Most agreements sit between 24 and 60 months; anything shorter or longer needs a funder check before you rely on it. |
| Age of the asset | There is no single cut-off. It depends on the asset class, and condition, hours and resale value are underwritten rather than the year alone. Tell us the age and we will say before you commit. |
| Buying from a private seller | Often possible, but case by case. It needs a funder who will write it, an inspection and proof of ownership, so say whether the seller is a dealer or a private seller when you enquire. |
| Deposit | Frequently nil where the credit profile is standard. Where it is not, typically 10–20%, nearer 20% if a default is recent. |
| VAT on the purchase | Both approaches exist, depending on the funder. The agreement is commonly written on the ex-VAT price with the VAT paid upfront and reclaimed, though some funders will include the VAT in the agreement. |
General guidance from our own funder panel as at 31 October 2026, not a quote and not an offer of finance. All finance is subject to status and to the funder's own criteria.
Why is a digital press easier to finance than a server room?
Because a funder can sell it. Presses are serialised industrial machines with dealers across Europe who buy and refurbish them, and click counts give a verifiable measure of remaining life. That real recovery value changes the whole underwriting posture, whereas a server room leaves a lender with little more than your promise to pay.
Can a used press be financed?
Yes, and it is common in the print trade. Funders will look at the click count, the service record, who is supplying and installing it, and whether a warranty is included. Age alone matters far less than usage. An independently inspected machine from a recognised dealer is a perfectly normal proposition.
Can finishing equipment go on the same agreement?
Yes, and it usually should, since a press without matching finishing capacity creates a bottleneck. Creasers, folders, booklet makers and cutters are all solid assets in their own right with their own trade market. Funding the line as one project also tends to produce a more coherent application.
How does the click charge work alongside the finance?
The finance covers the machine; the click charge covers toner, parts and engineer attendance and is billed by the manufacturer or dealer on meter readings. They run in parallel. Understand your expected volume before committing, because click rates are usually tiered and the assumptions matter to your job costings.
We have won a contract that needs more capacity. Does that help the application?
Considerably. A named contract or framework behind the investment is the single most useful thing you can put in front of an underwriter. It shows the machine has work waiting rather than being bought in hope. Supply the paperwork if you have it, redacted where commercially sensitive.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Illustrative only, not a quote, a flat rate is not an APR, so the APR on a given agreement will be higher. VAT and fees excluded.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 19 Google reviews
Thinking about production print finance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
