HMRC Time to Pay Explained
How an HMRC payment plan works, who qualifies, what it costs — and when borrowing is the better option.
- Whole-of-market — 60+ lenders searched
- All credit histories considered
- Decisions in as little as 24 hours
Whole-of-market — 60+ lenders searched, including
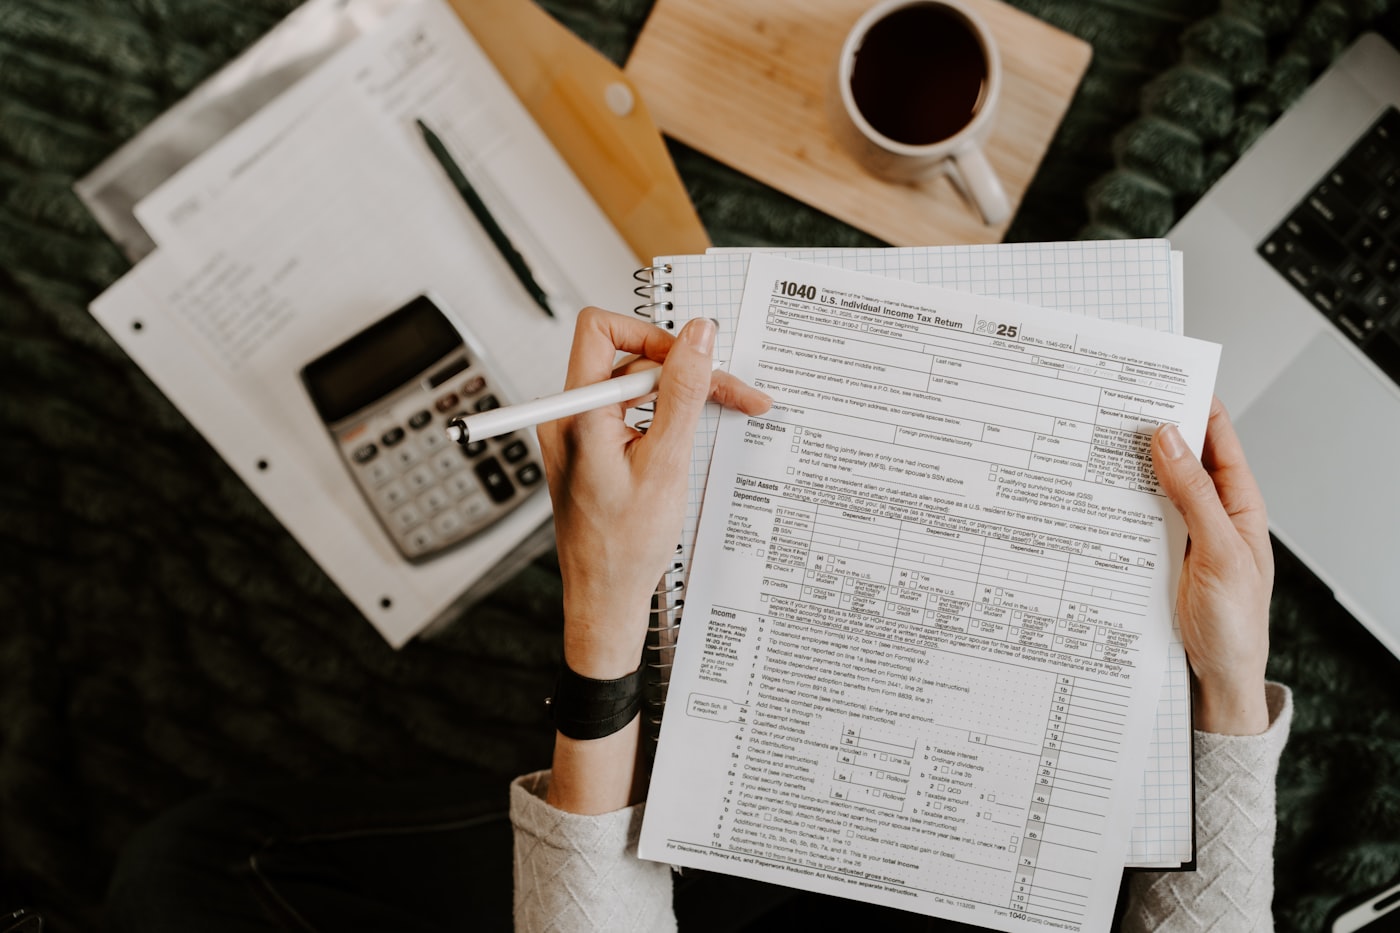
If you cannot pay a tax bill on time, an HMRC Time to Pay arrangement is usually the first thing to explore. It lets you spread the liability in instalments and there is no arrangement fee. This page explains how it works, because we would rather you used the cheaper option where it fits.
What you can fund
Corporation tax
CT600 liabilities where TTP is refused.
VAT
Quarterly returns needing longer than HMRC offers.
PAYE & NIC
Payroll liabilities spread further.
Self assessment
Personal and partnership liabilities.
Repeat requests
Where a further arrangement is unlikely.
Tender protection
Keeping arrangements off your record.
What a Time to Pay arrangement is
A Time to Pay arrangement is an agreement with HMRC to settle a tax liability in instalments rather than in one payment. It applies to corporation tax, VAT, PAYE and self assessment. It is not a product you buy — it is a negotiated arrangement, granted at HMRC’s discretion.
How to request an HMRC payment plan
Contact HMRC before the deadline, not after. Approaching them early, with figures ready and a realistic proposal, materially improves the outcome. Be prepared to explain why you cannot pay, what you can pay, and over what period. HMRC will want to understand the business rather than simply granting a delay.
Does it cost anything?
There is no arrangement fee, but interest accrues on the outstanding amount for the period of the arrangement. That interest is generally cheaper than commercial borrowing, which is why Time to Pay is usually the first option worth trying.
Who tends to be granted one
Businesses with a genuine short-term difficulty, a clean filing and payment history, and a credible plan. Repeated arrangements, unfiled returns or a pattern of late payment make refusal considerably more likely.
When Time to Pay is not the answer
There are real situations where borrowing is better:
- HMRC refuses. It is discretionary, and refusal happens — particularly on repeat requests.
- The period offered is too short. HMRC may agree to three months where you need nine.
- You need certainty now. A negotiation takes time; a facility can be arranged in days.
- Compliance record matters to you. Some businesses would rather not carry an arrangement, particularly when tendering for contracts where financial standing is assessed.
- The arrangement would restrict you. Being in a Time to Pay arrangement can affect other borrowing while it runs.
What happens if you do nothing
This is the option to avoid. Late payment attracts interest and penalties, and HMRC has strong recovery powers including direct recovery from bank accounts and, ultimately, winding-up proceedings. Whichever route you take, take one.
This page is general information, not tax advice — speak to your accountant about your own position.
See also: corporation tax loans or VAT loans if Time to Pay is not available to you.
How it works
Tell us what you need
One quick conversation about the asset and how the repayments need to work.
We search 60+ lenders
As an independent broker we find the right structure and rate — not one lender’s products.
You get funded
Indicative decisions in as little as 24 hours, then we manage it through to payout.
Estimate your repayments
Asset finance is quoted on a flat rate, so that is what the buttons show, with the equivalent APR beside it. Your exact rate depends on the asset, the term, the deposit and the lender.
Prime is an established, profitable business with clean credit. Specialist covers newer businesses and credit that needs explaining — the asset itself carries part of the risk, which is why finance is often available where an unsecured loan is not.
Representative example: on Hire Purchase, borrowing £25,000 over 48 months at a 5.15% flat rate (equivalent to 9.9% APR representative), you would repay around £628 a month; total amount repayable approximately £30,150, of which £5,150 is the cost of finance. This calculator is for illustration only — it is not a quote or an offer of finance, and the rate and repayments you are offered will depend on the asset, term, deposit and your circumstances. CW Asset Finance is a credit broker, not a lender, and will receive a commission from the lender that funds your agreement. All finance is subject to status, affordability and lender approval.
Rates shown are indicative flat rates with the equivalent APR alongside — the two are not the same number. Indicative only and does not constitute a quote or an offer of finance. Subject to status and lender approval.
Frequently asked questions
What is an HMRC Time to Pay arrangement?
How do I set up an HMRC payment plan?
Does an HMRC payment plan cost anything?
Can HMRC refuse Time to Pay?
Is a tax loan better than Time to Pay?
Does being in a Time to Pay arrangement affect other borrowing?
Do you cover my area?
Get your quote
Tell us what you’re looking to fund and Conor will come back to you personally — usually the same day.
Prefer to talk? Call 0333 772 4864 · serving Leeds, York, Harrogate, Wakefield, Selby, Tadcaster & across North & West Yorkshire.