
Induction hob finance
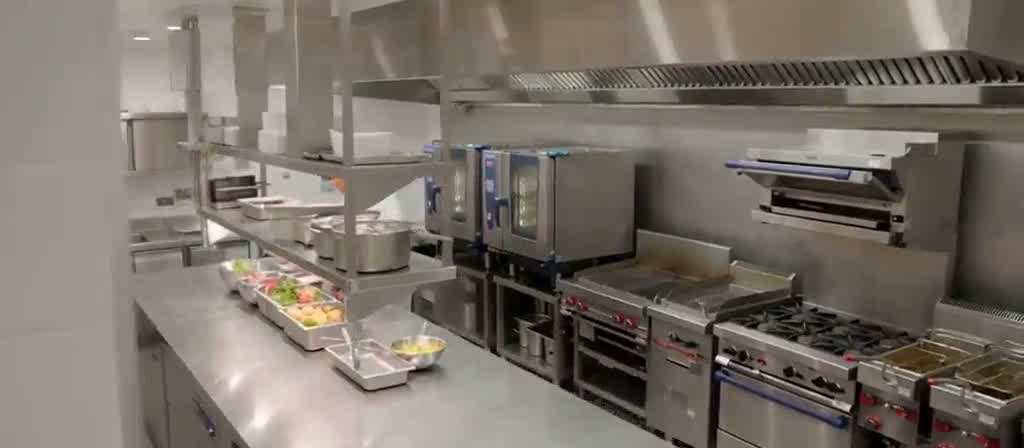
Kitchens moving off gas want induction for the heat, the speed and the electricity bill, and the switch is far easier to justify when it is spread.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersWhole-of-market panel, not one bank
- 5.0 from 19 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes. Commercial induction hobs are funded as ordinary equipment on hire purchase or lease, either as countertop units or as induction modules within a cookline. Used units from trade dealers are fundable, though the market is thinner than for gas because induction is newer. The detail that catches people out is the electrical supply. Swapping a gas suite for induction often needs a bigger incoming supply, a new distribution board or a DNO application, and that work is a building cost with no resale value, so funders will fund the hobs and leave the electrics to you.
Who finances this
Restaurants and hotels moving off gas for energy cost or for kitchen comfort, dark kitchens and delivery-only sites where there is no gas supply at all, and hotels running live cooking stations in a breakfast room or at events. There is also a steady flow from care homes and schools where open flame is unwelcome. The trigger is usually a refurbishment, a landlord withdrawing gas, or a chef who has cooked on induction elsewhere and will not go back.
How lenders see it
Induction units are branded, serial numbered and portable, which makes them easier to recover than almost anything else in a kitchen, so funders are comfortable with the asset itself. Resale values are reasonable but not spectacular, partly because glass tops chip and partly because the used market is still shallow. As ever in hospitality, the credit decision is about the operator rather than the hob: length of trading, accounts, bank conduct, whether the site is a first venture. The electrical infrastructure is the part to watch. Supply upgrades and board work are classed as soft, non-recoverable cost, and where they outweigh the equipment itself a funder may prefer to write the whole thing as an unsecured business loan instead.
Buying used
Yes, though more cautiously than gas equipment. Dealers do supply refurbished induction units and funders accept them, typically at a lower age limit because the electronics date faster than a cast-iron burner.
Also in catering and hospitality finance
See everything we fund in catering and hospitality finance →
Funding a seasonal trade
Flowzo funds restaurants, pubs and cafes against card takings rather than filed accounts, useful when the kit is bought and the quiet months still have to be covered.
Machines we have funded
| Falcon Dominator Plus induction hob | Heavy-duty four-zone induction top |
|---|---|
| Lincat Opus 800 induction hob | Modular induction top for cooking suites |
| Blue Seal Evolution induction range | Induction cooking module with oven base |
| Adventys induction hobs | French-built countertop induction tops |
| Target Catering Equipment induction suites | Bespoke British-built induction suites |
| Roller Grill induction hobs | Countertop single and twin induction units |
| Buffalo induction hobs | Entry-level countertop induction hobs |
| Electrolux Professional thermaline induction tops | Induction modules for bespoke suites |
| Zanussi Professional induction tops | Modular induction cooking tops |
Can the electrical upgrade be included in the finance?
Sometimes a proportion, rarely all of it. Cabling, boards and a DNO supply increase are works on the building, not equipment, so most funders exclude them. Where the hobs make up the bulk of the invoice and the business is well established, some will allow the installation as a minor soft cost. Get it quoted as a separate line either way.
Is induction worth financing when the pans have to be replaced too?
Ferrous pans are a real cost and worth budgeting for, but they are consumables rather than assets, so they will not go on an asset agreement. What some operators do is fund the hobs and put the pan replacement on a short working capital facility, or simply absorb the pans and fund the hardware that has a serial number.
Can I finance induction for a dark kitchen with no gas supply?
Yes, and delivery-only kitchens are a growing part of this market. The funder will want to understand the site: who your landlord is, whether you hold a licence or a lease, and how long you have been trading. Short licence agreements in shared kitchen facilities can be a sticking point, so have your paperwork ready.
Do induction hobs hold their value for a funder?
Reasonably, but not as well as heavy cast cooking equipment. The electronics and the ceramic top age, and the second-hand market is smaller than for a Falcon gas range. That means the funder leans more heavily on your accounts than on the kit, so a strong trading record matters more than which brand you specify.
Can I mix induction and gas on one finance agreement?
Yes. A mixed cookline with induction zones, a gas range and a chargrill goes onto a single schedule perfectly happily, and funders prefer it because a bigger, varied asset list is easier to place than one small hob. It also leaves you with one payment and one end date rather than three.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Illustrative only, not a quote, a flat rate is not an APR, so the APR on a given agreement will be higher. VAT and fees excluded.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 19 Google reviews
Thinking about induction hob finance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
