
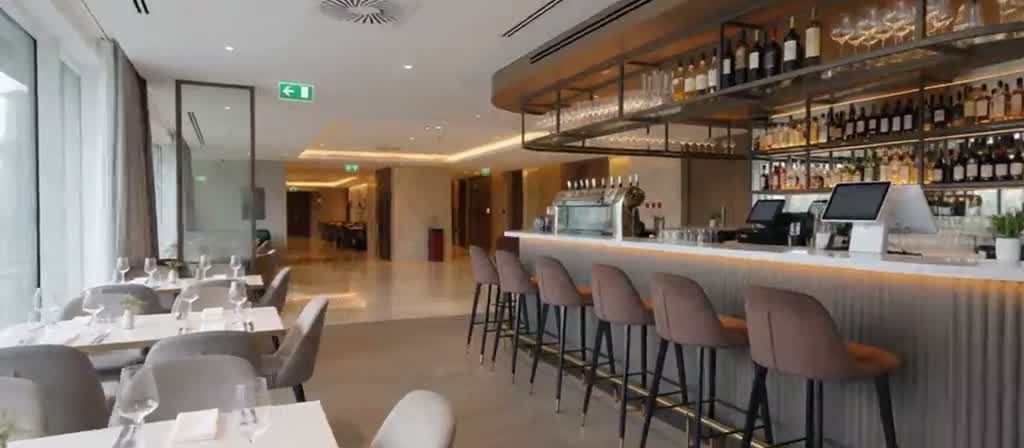
Bar fit-out finance
A refurbishment is bought on the promise of better spend per head, and the whole point is that it should not swallow a season of cash to get there.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersWhole-of-market panel, not one bank
- 5.0 from 19 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes, although not usually as classic asset finance for the whole project. A bar fit-out is mostly joinery, counters, flooring, lighting and decoration, all of which become part of the building and cannot be recovered, so funders treat them as soft costs. The equipment within it, bottle coolers, glasswashers, ice machines, dispense, is fundable as assets. In practice a fit-out is funded either as a mixed facility where the equipment carries the soft costs, or as an unsecured business loan assessed on your trading.
Who finances this
Licensees taking on a tired site and repositioning it, pub companies and independent operators doing a planned refurbishment cycle, and restaurants adding or rebuilding a bar to grow wet sales. The trigger is usually competitive or contractual: a new venue has opened nearby, or a pub company requires investment as a condition of a new agreement. Hotels rebuild lobby bars when the food and beverage offer is being repositioned.
How lenders see it
This is the softest end of hospitality funding. Fitted joinery, back bar shelving, counters and tiling are worth scrap value the moment they are installed, and a funder collecting them would spend more on labour than the timber is worth. So the lend is a credit decision, full stop: filed accounts, how long you have held the site, bank conduct, whether the premises are tied, and the director’s own position. The useful lever is the equipment. Gamko and Osborne bottle coolers, a Classeq glasswasher, a Hoshizaki ice machine and the cellar plant are all genuine assets, and a facility built around them can often carry a proportion of the fit-out alongside. Where the ratio is wrong, an unsecured loan is the honest answer rather than dressing a refit up as equipment finance.
Buying used
Rarely for the fit-out itself, since fitted joinery cannot be moved economically. Yes for the equipment within it, where coolers and glasswashers from dealers are perfectly fundable.
Also in catering and hospitality finance
See everything we fund in catering and hospitality finance →
Funding a seasonal trade
Flowzo funds restaurants, pubs and cafes against card takings rather than filed accounts, useful when the kit is bought and the quiet months still have to be covered.
Machines we have funded
| Gamko MaxiGlass bottle coolers | Glass-door under-bar bottle coolers |
|---|---|
| Osborne under-bar refrigeration | Back bar coolers and bottle units |
| IMC under-bar modules | Stainless wells, sinks and speed rails |
| Autonumis dispense equipment | Fonts, coolers and dispense pumps |
| Angram beer engines | Hand pulls for cask ale service |
| Classeq G500 Duo | Undercounter glasswasher for busy bars |
| Hoshizaki IM-130NE | Under-bar cube ice machine |
| Williams undercounter fridges | Refrigerated prep counters for bars |
| Polar back bar display coolers | Entry-level bottle display coolers |
Why can I not fund a whole bar refurbishment on asset finance?
Because most of it is not an asset in the sense a funder means. Joinery, flooring, lighting and decoration become part of the building and cannot be recovered and sold, so there is no security behind the lend. Equipment can be funded on an agreement and the rest is assessed on your accounts, or funded as a business loan.
Can I mix equipment finance and a business loan for a refit?
Yes, and it is often the best structure. Fund the coolers, glasswashers, ice machine and cellar plant on an asset agreement, where the security helps, and cover the joinery and decoration with a loan sized against turnover. Two facilities for two very different types of cost usually beats forcing everything down one route.
Does being a tied tenant change what I can fund?
It affects the assessment rather than the availability. Tied operators have less control over margin, which underwriters take into account, and your agreement may restrict what you can alter or which equipment you can install. Check the terms with the pub company before you commit to a specification, not after the order is placed.
Will my landlord own the fit-out at the end of the lease?
Frequently, yes, and that is exactly why funders treat it as soft. Landlord fixtures pass with the premises, and your lease may also require reinstatement. Read the alterations and dilapidations clauses before you spend, because they determine whether you are investing in your business or in someone else’s building.
How much fit-out cost will a funder include alongside equipment?
It varies by funder and by how strong the rest of the invoice is. Where branded, recoverable equipment makes up the bulk of the order and your accounts are sound, a reasonable proportion of installation and fit-out can usually be carried. Where the equipment is a small part of a large refurbishment, the loan route is more realistic.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Illustrative only, not a quote, a flat rate is not an APR, so the APR on a given agreement will be higher. VAT and fees excluded.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 19 Google reviews
Thinking about bar fit-out finance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
