
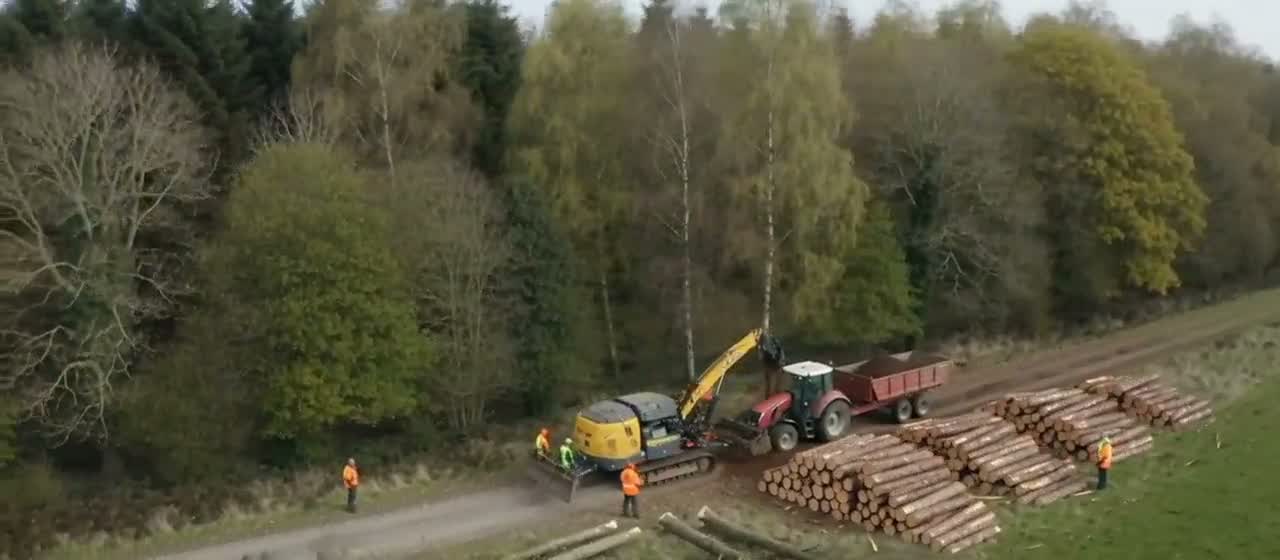
Skidder finance
Fund a cable or grapple skidder for whole-tree extraction and difficult ground, on new, used or imported machines.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersA panel of lenders, not one bank
- 5.0 from 20 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes, though the panel is narrower than for forwarders because skidders are less common in British forestry, where cut-to-length working dominates. That matters to a funder only because resale here is thinner, so they lean harder on the borrower and on the work behind the machine. The machines themselves are solid hard assets with serial numbers and international demand, and most skidders in the UK are bought used, often imported. Used purchases are entirely normal in this market. The recurring complication is title on imported machines: the ownership chain has to be evidenced before any funder will release money.
Who finances this
Contractors working steep or rocky ground where a forwarder cannot operate, firms clearing windblow after a storm, and operations extracting whole trees for biomass or for roadside processing. The trigger is frequently storm damage on a scale that has to be cleared fast. Some hardwood and estate contractors run skidders because the timber is long and irregular rather than neatly cut to length.
How lenders see it
Skidders go to specialist plant funders rather than a general panel, because a generalist underwriter may not have a comparable value to work from. Make, hours, winch or grapple condition and tyre state all feed the valuation, and a machine with a documented history will be valued more generously than one without. Because resale within the UK is slower than for mainstream forestry plant, funders look for contracted volume and relevant operating experience, and a strong personal covenant. Imports are frequent and need care: the seller invoice, proof of ownership, VAT treatment and the physical location of the machine all get checked before drawdown. Windblow work is unpredictable by nature, so a case built entirely on storm clearance will be questioned. Declines tend to follow thin trading history and unverifiable overseas sellers.
Buying used
Yes. Most skidders funded in the UK are used, and age is accepted where hours, tyres and drivetrain condition are documented.
Also in arb and forestry finance
See everything we fund in arb and forestry finance →
Funding the season, not just the chipper?
Farmzo handles rural working capital, wages, fuel and contracting costs between invoices.
Go to Farmzo → Or read how the two fit together
Buying forestry kit at a sale? We can give you an indicative decision before you bid, and we list every UK machinery auctioneer and livestock mart.
Machines we have funded
| Ecotrac 120V | Compact cable skidder for small blocks |
|---|---|
| Welte W130 | Cable skidder for steep ground |
| Welte W230 | Larger skidder for heavy extraction |
| HSM 805 | Forestry skidder with winch and blade |
| HSM 904 | High-power skidder for clear fell |
| John Deere 648L-II | Grapple skidder for production forestry |
| John Deere 748L-II | Large grapple skidder for long hauls |
| Tigercat 610E | Six-wheel grapple skidder |
| Tigercat 620E | High-capacity grapple skidder |
| Caterpillar 555D | Grapple skidder for heavy timber |
What a skidder actually costs to buy
Prices for a skidder advertised by UK suppliers run from £4,173 to £22,000 (checked 28 October 2026).
On the UK's own marketplace listing site, only 1 of the first 727 results for 'skidders for sale in the United Kingdom' was actually located in the UK (a 1991 Timberjack 450B in North Yorkshire at £22,000 on 500 hours after a Clark transmission rebuild); every other listing shown was a US, Canadian or New Zealand machine with its dollar price silently converted to £(a tell confirmed by odd endings like £112,076 and £30,012). The genuine UK/Ireland stock splits into two disconnected tiers with nothing in between: brand-new compact rubber-tracked mini-skidders from one Irish dealer at £4,173-£6,741 ex VAT, and a single 35-year-old full-size articulated skidder at £22,000.
| Machine | Asking price | Seen at |
|---|---|---|
| Delano T360, 2026, unused, rubber-tracked mini skidder, Ireland | £4,173 +VAT | mascus.co.uk |
| WTS 360, 2025, unused, rubber-tracked mini skidder, Ireland | £5,893 +VAT | mascus.co.uk |
| Machpro MPS360, 2025, unused, rubber tracks, hydrostatic transmission, integrated seat, Ireland | £6,741 inc VAT | mascus.co.uk |
| Timberjack 450B, 1991, 500 hours, 4WD, enclosed ROPS, Cummins 5.9 engine, Clark 3-speed transmission rebuilt <500hrs, Esco/Gearmatic winch | £22,000 VAT not stated | machinerytrader.co.uk |
Prices checked 28 October 2026 on machinerytrader.co.uk, mascus.co.uk. These are asking prices observed on dealer and marketplace listings, shown as examples. They are not a quote or an offer of finance, and they move with the market. Check the current advert before budgeting.
How finance works on a skidder
The prices above are what a seller is asking. What a funder will actually do with the purchase is a separate question, and it is the one that decides whether the deal happens.
| Question | Typical answer |
|---|---|
| Term available | 12 to 72 months. Most agreements sit between 24 and 60 months; anything shorter or longer needs a funder check before you rely on it. |
| Age of the asset | There is no single cut-off. It depends on the asset class, and condition, hours and resale value are underwritten rather than the year alone. Tell us the age and we will say before you commit. |
| Buying from a private seller | Often possible, but case by case. It needs a funder who will write it, an inspection and proof of ownership, so say whether the seller is a dealer or a private seller when you enquire. |
| Deposit | Frequently nil where the credit profile is standard. Where it is not, typically 10–20%, nearer 20% if a default is recent. |
| VAT on the purchase | Both approaches exist, depending on the funder. The agreement is commonly written on the ex-VAT price with the VAT paid upfront and reclaimed, though some funders will include the VAT in the agreement. |
General guidance from our own funder panel as at 31 October 2026, not a quote and not an offer of finance. All finance is subject to status and to the funder's own criteria.
Why are skidders harder to finance than forwarders?
Because British forestry mostly works cut-to-length, so there are fewer skidders in the country and fewer buyers if a machine has to be sold. That thinner resale market makes generalist funders cautious, and the case moves to specialist plant lenders who understand the values and the export options behind them.
Can I finance a skidder imported from North America or Europe?
Yes, with the right preparation. The funder needs a seller invoice, proof the seller owns the machine, clarity on VAT and import duty, and confirmation of where the machine is when payment is made. Many will only pay once it has landed in the UK, which affects how the purchase is structured.
Is storm clearance work enough to justify the machine?
On its own, it is a difficult argument. Windblow is unpredictable, and funders will not underwrite a machine on the expectation of bad weather. Where storm work sits alongside regular thinning or extraction contracts, it strengthens the case. Presented as the sole income, it reads as speculative.
What condition points do valuers look at on a used skidder?
Hours, engine and transmission condition, tyres, the winch or grapple, and evidence of arch and boom repairs. Skidders work hard in abrasive conditions so wear is expected, but unrecorded structural repair is a concern. A documented service history has a real effect on the valuation and therefore on the advance.
Do I need forestry experience to be approved?
It carries genuine weight on specialist machines. Funders are more comfortable when the applicant has operated in the sector, because the machine only earns in competent hands. Years of employed forestry work before going out on your own is worth stating clearly on the application; it is not something underwriters infer.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Total repayable about £,
Illustrative only, not a quote. Flat rates are indicative, subject to status and are not an APR. Figures are for limited companies on unregulated agreements and exclude VAT and fees. Sole traders and partnerships borrowing £25,000 or less may be regulated and are quoted differently.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 20 Google reviews
Thinking about skidder finance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
