
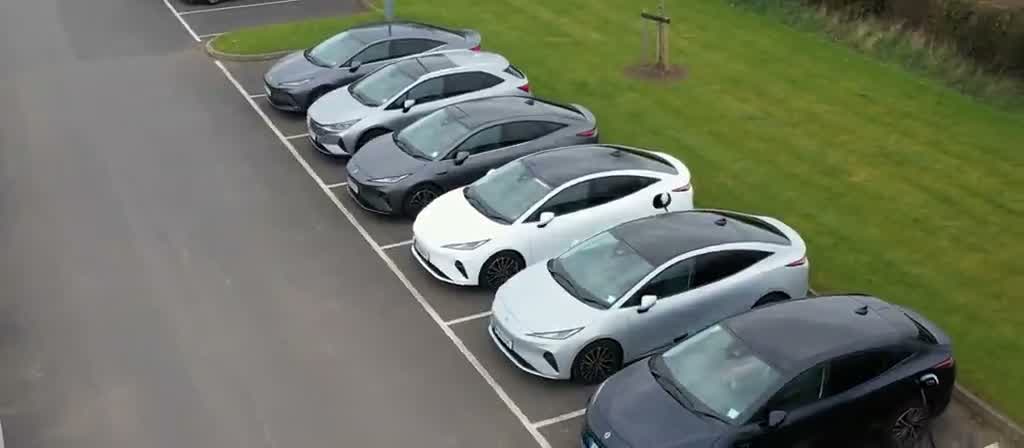
Business fleet finance
One facility covering several cars, so a growing sales team does not mean a fresh credit application every time you hire.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersWhole-of-market panel, not one bank
- 5.0 from 19 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes. Where a business needs several cars, funders will set a facility limit for the company and draw each vehicle down against it as a separate schedule, rather than underwriting every car from scratch. Hire purchase, finance lease and contract hire can all sit under this structure, and vehicles can be added as drivers join. The thing that catches businesses out is that the limit is set against the company’s current accounts, not its plans, so if you expect the fleet to grow quickly, say so at the outset and have the limit sized for that, because going back for a substantial increase shortly afterwards is treated as a new credit decision.
Who finances this
Companies running a handful of vehicles and upward, field sales teams, multi-site service businesses, recruitment and estate agencies, care providers with visiting staff. The trigger is usually growth outpacing an ad hoc approach, several agreements ending at the same time, or a finance director tired of chasing separate renewal dates and V5s across half a dozen funders.
How lenders see it
Fleet underwriting is a company exercise before it is a vehicle exercise. Funders size a limit against filed accounts, net worth, sector and how existing facilities have been run, then treat individual cars as drawdowns within it. They pay attention to concentration, a fleet of identical models all returning in the same month creates a residual value cluster they would rather avoid, and to mileage profiles, because a heavily used fleet comes back in poorer condition. Vehicle choice policy helps: mainstream marques with deep used demand support a better structure than an eclectic mix. Where the business is a limited company they read the balance sheet; where it is a partnership or a group, they will want to see the wider structure and may ask for cross-guarantees. Declines usually come from overtrading or from a limit request that has no relationship to turnover.
Buying used
Yes, and mixing used and new vehicles under one facility is common
What would a business fleet cost per month?
Cars are treated differently from commercial vehicles. A van generally qualifies for the annual investment allowance ; a car generally does not, and instead attracts writing-down allowances tied to its CO 2 emissions, with fully electric cars in the most favourable position. A car made available for private use also creates a benefit in kind for the driver. The rules change between budgets and your position depends on how you trade, so treat this as the direction of travel and get your accountant to confirm the detail before you commit.
Also in business car finance
See everything we fund in business car finance →
Machines we have funded
| Volkswagen Passat Estate | Sales fleet estate for high mileage |
|---|---|
| Skoda Octavia Estate | Value fleet car with large boot |
| BMW 3 Series Saloon | Premium user-chooser compact executive |
| Audi A4 Avant | Premium estate for regional managers |
| Kia Sportage | Fleet SUV with long warranty cover |
| Tesla Model 3 | Fleet electric saloon with low tax cost |
| Volkswagen Golf | Compact pool car for mixed duties |
| Volvo XC40 | Premium compact SUV for user-choosers |
| Hyundai Ioniq 5 | Electric crossover for fleet electrification |
| Toyota Corolla Touring Sports | Hybrid estate for high mileage reps |
How many cars do I need for a fleet facility?
There is no fixed threshold, but a block facility starts to earn its keep once you are running a handful of vehicles or expect to add cars through the year. Below that, individual agreements are usually simpler. The real test is whether you are repeating the same application process often enough for it to be a nuisance.
Can I add cars to the facility later?
That is the point of it. Once the limit is agreed, each new vehicle is drawn down against it with far lighter paperwork than a fresh application. You can keep adding until the limit is used. Increasing the limit itself is a new credit decision, so size it for where the business is heading rather than where it is today.
Do all the cars have to be the same make?
No, and funders often prefer a spread because it avoids a cluster of identical vehicles hitting the used market together. What helps is a sensible vehicle policy, mainstream marques with strong used demand across the fleet, rather than a completely open choice that produces hard-to-value cars.
Can drivers choose their own cars?
Within a policy, yes. Most businesses set bands by role and let drivers choose inside them, which keeps staff happy without leaving the fleet unfundable. Give us the policy and we will tell you where it will cause valuation problems, usually unusual colours, niche models and very high optional specification.
Who handles the paperwork for a fleet?
We do, as the broker. One facility means one set of company documents, then a schedule per vehicle with its own delivery date and details. You still hold V5s and insurance obligations per car, but you are not repeating accounts, bank statements and director information for every single order.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Illustrative only, not a quote, a flat rate is not an APR, so the APR on a given agreement will be higher. VAT and fees excluded.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 19 Google reviews
Thinking about business fleet finance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
