
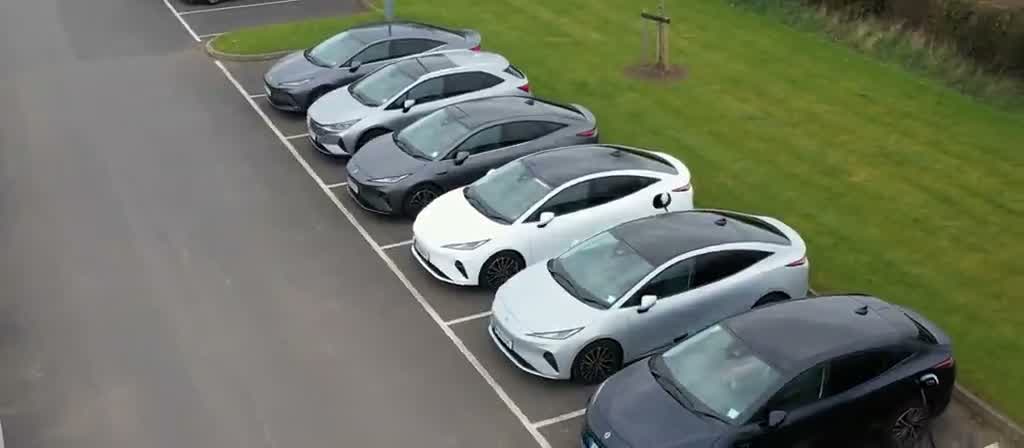
Electric company car finance
Business funding for a fully electric company car, where the tax treatment is the reason most people make the switch in the first place.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersWhole-of-market panel, not one bank
- 5.0 from 19 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes. An electric company car is funded through the business on hire purchase, finance lease or contract hire in exactly the same way as a petrol or diesel one. What differs is the tax. Cars do not usually get the annual investment allowance that vans do; they get writing-down allowances linked to CO2 emissions, and a fully electric car sits in the most favourable position available. Benefit in kind on an electric company car is also far lower than on an equivalent petrol or diesel model. The catch is residual value: EV used prices have moved sharply, so funders are more cautious about what the car will be worth at the end than they are about the car itself.
Who finances this
Companies switching a director or sales car to electric because the benefit-in-kind saving finally outweighs the range inconvenience. Often prompted by an accountant, a salary-sacrifice conversation that did not work, or a charger already installed at the business premises. Also businesses with depot-based drivers doing predictable daily mileage, where the running cost per mile is the main argument rather than the tax position.
How lenders see it
Funders like the covenant on EV deals and worry about the asset. The company side is assessed as normal, accounts, conduct, director guarantee where appropriate. The asset side is where EVs get their own treatment: used values on some electric models fell faster than the original residual forecasts, so lenders have repriced their risk and are noticeably more comfortable with mainstream, high-volume EVs than with early-generation or low-demand models. Battery health and warranty transferability come up on used EVs. A contract hire funder carries the residual risk themselves, which is exactly why many businesses choose it for an EV, while on hire purchase the risk sits with you. Declines are rare on asset grounds alone; they are usually about the company, or about an EV priced well above what the business can support.
Buying used
Yes, though used EVs face tighter age limits with some funders and a battery health check
What would an electric company car cost per month?
Cars are treated differently from commercial vehicles. A van generally qualifies for the annual investment allowance ; a car generally does not, and instead attracts writing-down allowances tied to its CO 2 emissions, with fully electric cars in the most favourable position. A car made available for private use also creates a benefit in kind for the driver. The rules change between budgets and your position depends on how you trade, so treat this as the direction of travel and get your accountant to confirm the detail before you commit.
Also in business car finance
See everything we fund in business car finance →
Machines we have funded
Typically £20,259–£52,206 to buy. New electric cars at UK on-the-road RRP, Fiat Grande Panda Electric up to BMW iX3.Checked 2026-10-18.
| Tesla Model 3 | Electric saloon, the fleet favourite |
|---|---|
| Tesla Model Y | Electric crossover with big boot |
| Polestar 2 | Electric fastback for user-chooser lists |
| BMW i4 | Electric compact executive gran coupe |
| Audi Q4 e-tron | Electric premium SUV for company drivers |
| Mercedes-Benz EQE | Electric executive saloon for senior staff |
| Volvo EX40 | Electric compact SUV with good safety kit |
| Kia EV6 | Electric crossover with fast charging |
| Hyundai Ioniq 5 | Electric family car with long range |
| Volkswagen ID.7 | Electric saloon for high mileage drivers |
Is an electric car better for tax through a company?
Directionally, yes. Fully electric cars attract the most favourable capital allowance treatment available to cars, and benefit in kind on an EV is substantially lower than on a comparable petrol or diesel. We will not quote you rates or percentages, they change and your position is specific, so have your accountant run the actual numbers before you commit.
Should I lease or buy an electric company car?
It comes down to who you want holding the residual value risk. On contract hire the funder sets a future value and carries it, which many businesses prefer given how EV used prices have moved. On hire purchase you own the car at the end and take the upside or the downside yourself. Neither is universally right.
Can I finance a used electric car through my business?
Yes, and it is increasingly common now that used EV supply has built up. Funders will want to see reasonable battery state of health and whether the manufacturer battery warranty transfers. Age and mileage limits are tighter on used EVs than on used petrol cars with some lenders, so it helps to tell us the exact vehicle early.
Does the charger count as part of the finance?
A workplace charging point is a fixed asset rather than part of the car, so it is normally funded separately, often on a small equipment finance facility, and sometimes bundled by the dealer into the vehicle deal. If you want both arranged together, tell us at the enquiry stage and we will structure it rather than bolting it on late.
What happens to an EV lease if battery range drops?
Contract hire agreements are written against mileage and condition, not against battery performance, so normal degradation within manufacturer tolerance is not a breach. Significant capacity loss is usually a warranty matter with the manufacturer. Where it does bite is on a hire purchase car you intend to sell on, because poor battery health will show up in the trade value.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Illustrative only, not a quote, a flat rate is not an APR, so the APR on a given agreement will be higher. VAT and fees excluded.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 19 Google reviews
Thinking about electric company car finance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
