
Top dresser finance
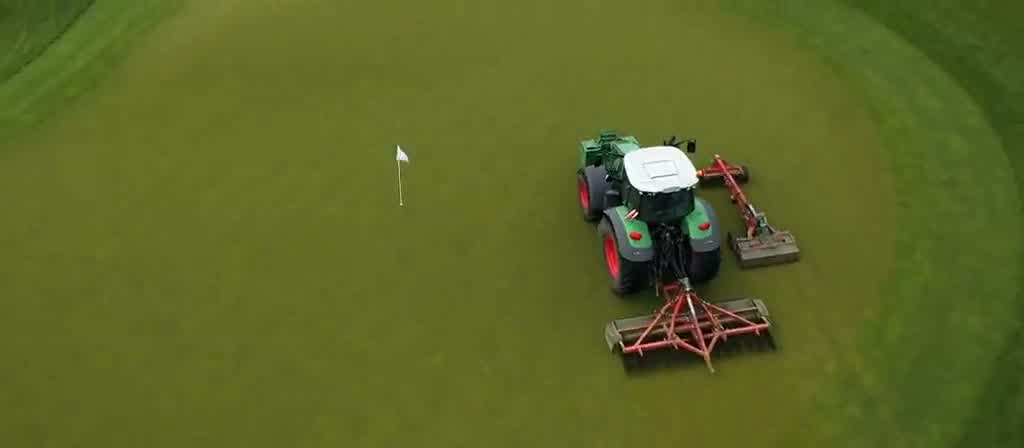
Top dressers spread sand and dressing evenly across greens and fairways, and the towed and truck-mounted units fund as standard turf plant.
Not picked a machine yet? See used turf care machinery from UK dealers, priced per month, on Groundcare Monthly.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersA panel of lenders, not one bank
- 5.0 from 20 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes. Top dressers fund as hard assets, whether towed hoppers, truck-mounted units or larger material handlers. Used machines are readily fundable because the construction is simple and there is a consistent second-hand market. The complication is that a truck-mounted dresser needs a utility vehicle to carry it, and clubs sometimes fund the dresser while assuming the existing vehicle will cope with the payload. It often will not. Confirm the carrying capacity first, and if the vehicle needs replacing, fund both on one agreement rather than discovering the gap after delivery.
Who finances this
Courses that have committed to a regular light dressing programme rather than two heavy applications a year, usually after an agronomy report linking organic matter to poor winter surfaces. Also sports turf contractors offering dressing as part of renovation packages, and cricket and racecourse grounds staff handling large volumes of loam and sand in a tight window. Most buyers have already tried hiring a dresser and found it unavailable in the fortnight they needed it.
How lenders see it
A top dresser is mechanically uncomplicated, which underwriters like, fewer things to fail means fewer arguments about condition at the end of an agreement. Dakota, Ty-Crop and Redexim units retain recognisable value and sell on through the same dealer network that sold them. Where a funder pays attention is the buyer’s wider position. Dressing programmes are usually part of a larger capital plan, so the club may be funding a mower and an aerator in the same year, and the underwriter looks at the total commitment rather than this one item. A members’ club is judged on subscription income, a proprietary course on trading, a contractor on the venues under contract. Spring and autumn weighting of repayments is accepted. Declines follow clubs stacking several agreements without the income to carry them all.
Buying used
Yes, used top dressers fund well, often to around ten years old, since the hopper and conveyor are the asset and both are easy to inspect.
Also in golf, turf and groundcare finance
See everything we fund in golf, turf and groundcare finance →
Buying groundcare machinery at auction? We can give you an indicative decision before you bid, and we list every UK machinery auctioneer and livestock mart.
Machines we have funded
Typically £1,200–£12,950 + VAT to buy. Used and ex-demo top dressers, from a Turfco spin dresser up to trailed bulk machines such as the Stargreen TD1500T.Checked 2026-10-18.
| Redexim Rink DS800 | Compact top dresser for greens |
|---|---|
| Redexim Rink SP1500 | Spinner top dresser for fairways |
| Ty-Crop MH-160 | Small material handler for tees and greens |
| Ty-Crop MH-400 | Material handler for bulk topdressing |
| Toro ProPass 200 | Top dresser with twin spinner discs |
| Dakota 410 Turf Tender | Towed top dresser with conveyor spread |
| Dakota 412 | Top dresser for sand and compost mixes |
| Dakota 440 | Larger capacity turf tender for fairways |
| Charterhouse Rink top dressers | Mounted and trailed dressing units |
| Trilo material spreaders | Spreaders for sand and soil dressings |
Will our utility vehicle carry a truck-mounted dresser?
Check the payload rating before ordering. A loaded hopper is heavy and light utility vehicles are not always rated for it. If the vehicle is borderline, tell us early, funding a dresser and a suitable carrier together is straightforward, retrofitting the solution is not.
Can the sand or dressing material be financed?
No. Sand, loam, compost and seed are consumable trading costs and cannot go into an asset agreement. Only the machine can be funded. If cash flow around materials is the issue, that is a working capital conversation rather than an asset finance one. We can point you towards the right route if that is the real issue.
Is a towed dresser easier to fund than a mounted one?
Slightly, because it is a complete standalone asset with its own identity and does not depend on another vehicle. Both fund, but a towed unit avoids the question of what it is mounted on, which removes one step from the underwriting. Either way it is the machine itself that is being assessed.
We want a dresser and an aerator this year. One agreement or two?
Usually one. Combining assets on a single agreement means one credit application, one set of documents and often a better outcome than two smaller facilities. If the items are being delivered months apart we may split them, but we would explain why first. Deliveries in different seasons are the usual reason.
Do brush and drag mat attachments count?
If they are supplied and invoiced with the machine, yes. Brushes and mats bought separately from a groundcare catalogue later on are consumables. It is a small point but it is the most common reason a funded amount comes in under what the club actually spent.
Still choosing the machine? Groundcare Monthly lists used turf care machinery from UK dealers, with a monthly finance price on every one.
See used turf care machinery for sale on Groundcare MonthlyTell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Total repayable about £,
Illustrative only, not a quote. Flat rates are indicative, subject to status and are not an APR. Figures are for limited companies on unregulated agreements and exclude VAT and fees. Sole traders and partnerships borrowing £25,000 or less may be regulated and are quoted differently.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 20 Google reviews
Thinking about top dresser finance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
