
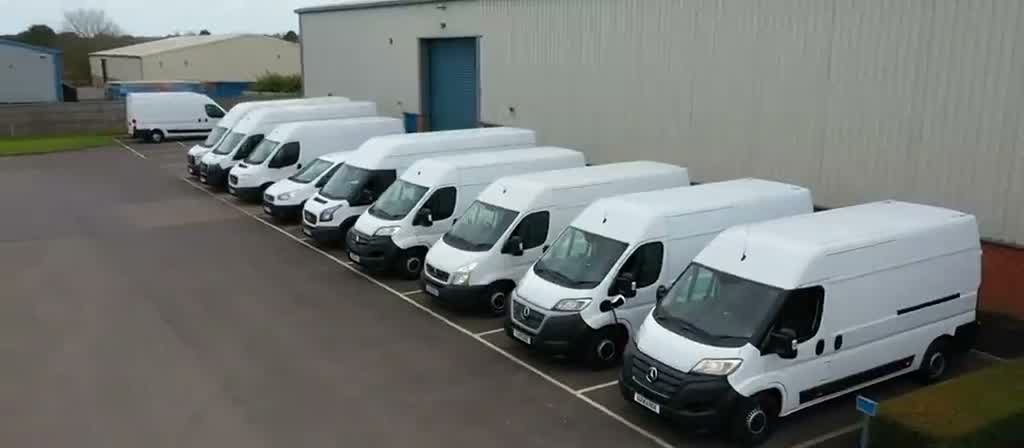
Large van finance
Maximum load cube on a standard licence, large panel vans funded for removals, couriers, installers and anyone shifting volume rather than weight.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersWhole-of-market panel, not one bank
- 5.0 from 19 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes. Large panel vans at the 3.5 tonne mark are funded routinely, normally on hire purchase or a lease in the business name. They sit in a slightly narrower resale market than medium vans, so a funder pays more attention to specification, wheelbase, roof height and payload all affect what it is worth second-hand. The issue that trips buyers up is weight rather than credit: once a large van is racked out, plated and loaded, staying inside the gross vehicle weight on a standard car licence gets tight, and that affects both insurance and what the vehicle is genuinely fit for.
Who finances this
Removals firms, kitchen and bathroom installers, shopfitters, parcel and pallet subcontractors, and event or AV crews who need volume. Often a business moving up from a medium van after repeatedly having to do two runs. Frequently bought by limited companies with a couple of years trading, and increasingly by courier subcontractors whose depot contract specifies a minimum load capacity before they can take a round.
How lenders see it
Large vans are still mainstream, but the panel narrows a little compared with medium stock because the used buyer pool is smaller and condition varies enormously. A tidy Sprinter or Crafter with sensible mileage places easily; a high-roof extra-long van that has spent four years on a parcel network is valued cautiously. Funders will ask what the van is used for, because removals and parcel work are high-wear applications and some lenders price or decline on sector. Limited companies with accounts are straightforward. Sole traders and newer businesses need either a deposit, a homeowner, or a contract to point at. The common declines are auction buys, vans with no service record, and applicants whose income all sits in cash with nothing showing through the bank.
Buying used
Yes. Used large vans are widely funded, though lenders look harder at service history and previous use than they do on a medium van of the same age.
Also in van and light commercial finance
See everything we fund in van and light commercial finance →
Van buying guides
We are a broker, not a dealer. We have no stake in which van you choose. These are written on that basis.
The van is one cost
Flowzo covers fuel, wages and the wait for customers to pay, working capital rather than the vehicle itself.
Machines we have funded
Typically £44,545–£63,635 + VAT to buy. New Ford Transit 3.5t panel van, MWB base diesel up to extra-long E-Transit, recommended retail price.Checked 2026-10-18.
| Mercedes-Benz Sprinter 315 L3H2 | Large van built for high mileage |
|---|---|
| Volkswagen Crafter CR35 L3H3 | High-roof large van for stand-up work |
| Peugeot Boxer L3H2 | Large van with big load volume |
| Citroen Relay L4H3 | Extra long high-roof large van |
| Vauxhall Movano L3H2 | Large van for removals and trade |
| Renault Master LL35 | Long large van with heavy payload |
| Ford Transit L4H3 Jumbo | Longest Transit for bulky freight |
| Iveco Daily 35S14 L4H2 | Truck-derived large van for heavy loads |
| Fiat Ducato L4H2 | Large van popular with converters |
| Maxus Deliver 9 L3H2 | Value large van with long warranty |
Can I drive a 3.5 tonne van on a normal licence?
A standard UK car licence generally covers vehicles up to 3,500kg gross weight. The issue is what you can carry once the van is converted, racked and fuelled, because the kerb weight eats into the payload. Check the plate on the van and weigh it loaded if you are close to the limit.
Does roof height affect the finance?
Not the application, but it affects the valuation. Extra-long, extra-high vans suit fewer buyers second-hand than a standard high roof, so funders value them a little more cautiously. It rarely stops a deal. It just means the lender figure may be lower than the advert price.
Can removals companies get van finance?
Yes, though some lenders treat removals as a higher-wear sector and underwrite accordingly. Showing regular contracted work, sensible mileage on your existing vehicles and a clean payment record all help. We know which funders are comfortable with the sector rather than pricing it as a risk.
Is a large van better bought new or used?
Used usually gives you far more vehicle for the outlay, but large vans work hard and a poorly maintained one is expensive. New gives you warranty cover and a known history. The right answer normally comes down to how many miles you will do a year and whether downtime costs you work.
Can courier subcontractors finance a large van?
Yes. Subcontractors on parcel and pallet networks are funded regularly. Lenders will want to see the depot agreement or remittances proving the round exists, since the income is the whole basis of affordability. Very new subcontractors with no payment history usually need a deposit.
Tell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Illustrative only, not a quote, a flat rate is not an APR, so the APR on a given agreement will be higher. VAT and fees excluded.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 19 Google reviews
Thinking about large van finance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
