
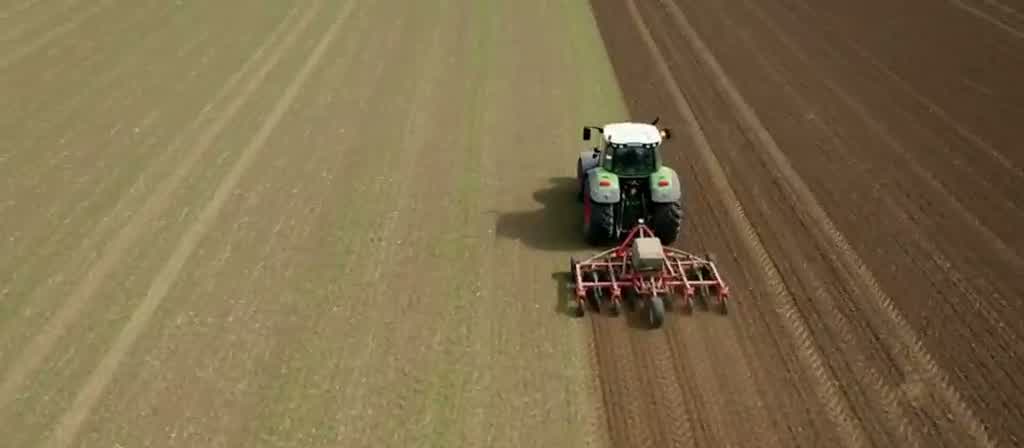
Plough finance
Funding for mounted and semi-mounted reversible ploughs, still the establishment tool of choice on heavy land and ahead of root crops.
Not picked a machine yet? See used cultivators, ploughs and drills from UK dealers, priced per month, on Tractor Monthly.
- FCA regulatedAppointed Representative, FRN 1031964
- 60+ lendersA panel of lenders, not one bank
- 5.0 from 20 Google reviews
- No credit checkEnquiring leaves no mark on your file
Yes, though a plough on its own is often a small enough purchase that it sits below where some funders begin. The usual route is to fund it with the tractor that will pull it, or alongside other cultivation equipment on a single invoice. Used ploughs are funded routinely and they hold value unusually well, because the frame outlasts several sets of wearing metal. The practical caution is matching: a plough specified for more furrows than the tractor can pull is a known reason for a funder to query an application, particularly where the tractor is also being financed.
Who finances this
Heavy land arable farms where ploughing still beats direct drilling in a wet autumn, root crop growers turning ground ahead of bed forming, and livestock farms ploughing out and reseeding leys. The trigger is commonly a move back to ploughing after a grass weed problem, a larger tractor that has left the existing plough undersized, or a frame that has been straightened once too often.
How lenders see it
Ploughs are among the simplest assets an agricultural funder handles. They have no engine, no electronics and a frame that lasts decades, so depreciation is slow and the secondhand market is national and consistently active. Underwriters check the make, the number of furrows, the condition of the headstock and legs, and whether the wearing metal is near the end of its life, since a full set of bodies is a meaningful cost on top of the purchase. The constraint is deal size rather than risk: many funders will not write an agreement for a single mounted plough, which is why they are usually bundled. Level repayments are standard, with harvest weighting available where the plough goes on the same agreement as a larger machine.
Buying used
Yes, readily, as frames outlast several sets of wearing parts
Also in rural and agricultural finance
See everything we fund in rural and agricultural finance →
Need the feed, not the tractor?
We fund the kit. Our farming arm Farmzo funds everything that is not kit, feed, fertiliser, seed, stock, tax bills and diversification, built around when a farm actually gets paid.
Go to Farmzo → Or read how the two fit together
Specialist agricultural funding
Machinery, livestock and land, each with its own page, because each is assessed differently.
Bidding at a farm sale or a dispersal? We can give you an indicative decision before you bid, and we list every UK machinery auctioneer and livestock mart.
Machines we have funded
| Kuhn Multi-Master 123 | Three and four furrow reversible plough |
|---|---|
| Dowdeswell DP Series | UK-built reversible plough for mixed soils |
| Kverneland 150 B Variomat | Reversible plough with variable furrow width |
| Kverneland 2500 i-Plough | Electronically controlled reversible plough |
| Lemken Juwel 8 | Mounted reversible plough with hydraulic reset |
| Lemken Diamant 16 | Semi-mounted plough for larger tractors |
| Kuhn Vari-Master L | Semi-mounted plough for heavy land |
| Gregoire Besson reversible ploughs | Mounted and semi-mounted heavy ploughs |
| Kverneland Packomat | Integrated furrow press for seedbeds |
| Kverneland disc coulters and skimmers | Plough body wearing parts and fittings |
What a plough actually costs to buy
Prices for a plough advertised by UK suppliers run from £1,950 to £25,850 (checked 28 October 2026).
Furrow count barely moves the price; the leg-protection mechanism does. Two 5-furrow ploughs sat £7,300 apart on the SAME furrow count: a Dowdeswell MA100 5-furrow (2002, DD bodies, shear-bolt protection) sold for £2,650, while a Kverneland ED100/200 5-furrow (2009, auto-reset, manual vari-width, No.28 bodies) sold for £9,950, nearly 4x. Auto-reset legs (which flex and self-right on a hidden obstruction instead of shearing a bolt) are the premium feature buyers actually pay for, not the furrow count advertised in the headline.
| Machine | Asking price | Seen at |
|---|---|---|
| Dowdeswell DP8B, 4 Furrow Reversible Plough | £1,950.00 VAT not stated | hollandagriculturalservices.co.uk |
| Dowdeswell MA100 Plough, 5 furrow, DD Bodies, 2002 | £2,650.00 VAT not stated | agri-linc.com |
| Kverneland 5 Furrow Reversible Plough | £4,500.00 VAT not stated | hollandagriculturalservices.co.uk |
| Dowdeswell DP100FS 5 Furrow Plough, 2003, Slatted Bodies, 14" Furrows | £6,450.00 VAT not stated | agri-linc.com |
| Kuhn 152 Vari-Master 6 Furrow Plough (5 plus 1), Hyd Vari-Width Auto-Reset, 2008 | £9,650.00 VAT not stated | agri-linc.com |
| Kverneland ED100/200 Plough 5-Furrow, 2009, auto-reset, manual vari-width, No.28 bodies | £9,950.00 VAT not stated | amtec-group.com |
| Kverneland ES85/200 Plough 4-Furrow, 2015, No.30 slatted bodies, hydraulic vari-width | £13,950.00 VAT not stated | amtec-group.com |
| Kuhn L55 Series Multi-Leader 7 Furrow, 2018, semi-mounted Plough, OnLand/In Furrow | £25,850.00 VAT not stated | agri-linc.com |
Prices checked 28 October 2026 on agri-linc.com, amtec-group.com, hollandagriculturalservices.co.uk. These are asking prices observed on dealer and marketplace listings, shown as examples. They are not a quote or an offer of finance, and they move with the market. Check the current advert before budgeting.
How finance works on a plough
The prices above are what a seller is asking. What a funder will actually do with the purchase is a separate question, and it is the one that decides whether the deal happens.
| Question | Typical answer |
|---|---|
| Term available | 12 to 72 months. Most agreements sit between 24 and 60 months; anything shorter or longer needs a funder check before you rely on it. |
| Age of the asset | There is no single cut-off. It depends on the asset class, and condition, hours and resale value are underwritten rather than the year alone. Tell us the age and we will say before you commit. |
| Buying from a private seller | Often possible, but case by case. It needs a funder who will write it, an inspection and proof of ownership, so say whether the seller is a dealer or a private seller when you enquire. |
| Deposit | Frequently nil where the credit profile is standard. Where it is not, typically 10–20%, nearer 20% if a default is recent. |
| VAT on the purchase | Both approaches exist, depending on the funder. The agreement is commonly written on the ex-VAT price with the VAT paid upfront and reclaimed, though some funders will include the VAT in the agreement. |
General guidance from our own funder panel as at 31 October 2026, not a quote and not an offer of finance. All finance is subject to status and to the funder's own criteria.
Can I finance a plough on its own?
Sometimes, but frequently the value is below where a funder will start. The straightforward fix is to buy it with the tractor or with other cultivation equipment and have the dealer invoice everything together. That produces one agreement at a value funders are happy to write.
Do lenders worry about worn shares and mouldboards?
They factor it in. Wearing metal is a consumable and a plough that needs a complete set of bodies is worth less than one recently refitted. It rarely changes the decision, but it can change the valuation, so it is worth asking the seller when the metal was last replaced.
Will a funder check that my tractor can pull it?
On a combined tractor and plough application, quite possibly. Specifying more furrows than the tractor can handle is a common mistake and an agricultural underwriter will spot it. It is also worth getting right for your own sake, since an over-specified plough simply will not work properly.
Do ploughs hold their value?
Better than most farm implements. With no engine or electronics to fail and a frame built to last decades, a well-kept plough from a mainstream manufacturer sells readily anywhere in the country. That reliability of resale is exactly why funders are relaxed about the asset itself.
Can a furrow press be included?
Yes, where it is bought at the same time and invoiced with the plough. Pressing behind the plough is standard practice on many farms and funding the pair together avoids splitting a single operation across two agreements. It also helps lift the deal above any minimum.
Still choosing the machine? Tractor Monthly lists used cultivators, ploughs and drills from UK dealers, with a monthly finance price on every one.
See used cultivators, ploughs and drills for sale on Tractor MonthlyTell us what you need
About a minute of plain questions, and no documents to dig out.
Prime is established and profitable with clean credit. Specialist covers newer businesses and credit that needs explaining, the asset carries part of the risk, so finance is often available where an unsecured loan is not.
Total repayable about £,
Illustrative only, not a quote. Flat rates are indicative, subject to status and are not an APR. Figures are for limited companies on unregulated agreements and exclude VAT and fees. Sole traders and partnerships borrowing £25,000 or less may be regulated and are quoted differently.
Start my enquiryNo credit check, and enquiring leaves no mark on your credit file. Finance is subject to status. We are a credit broker, not a lender.

Only pricing it up?
An enquiry is a conversation, not an application. Nothing runs against your file until you tell us to go ahead.
No credit check to enquire
Your credit scoreUntouched
Conor reads every enquiry himself. We will call you within 24 business hours, and it will be the person who actually arranges the finance, not a call centre, and not a form that disappears.
A real person on your side
One adviser from your first enquiry to the money in your account. No call centres.
Your adviser
Conor HullMon to Fri, 9am–6pm
5.0 from 20 Google reviews
Thinking about plough finance?
A few questions, and we will tell you what the panel can do. No obligation, and no call centres.
